Why Are Home Prices So High in San Diego?
San Diego price tags come from constrained supply, split submarkets and financing math — here is how to read each piece before you write an offer.
By Maren Vickery · Oct 06, 2026 · 9 min read
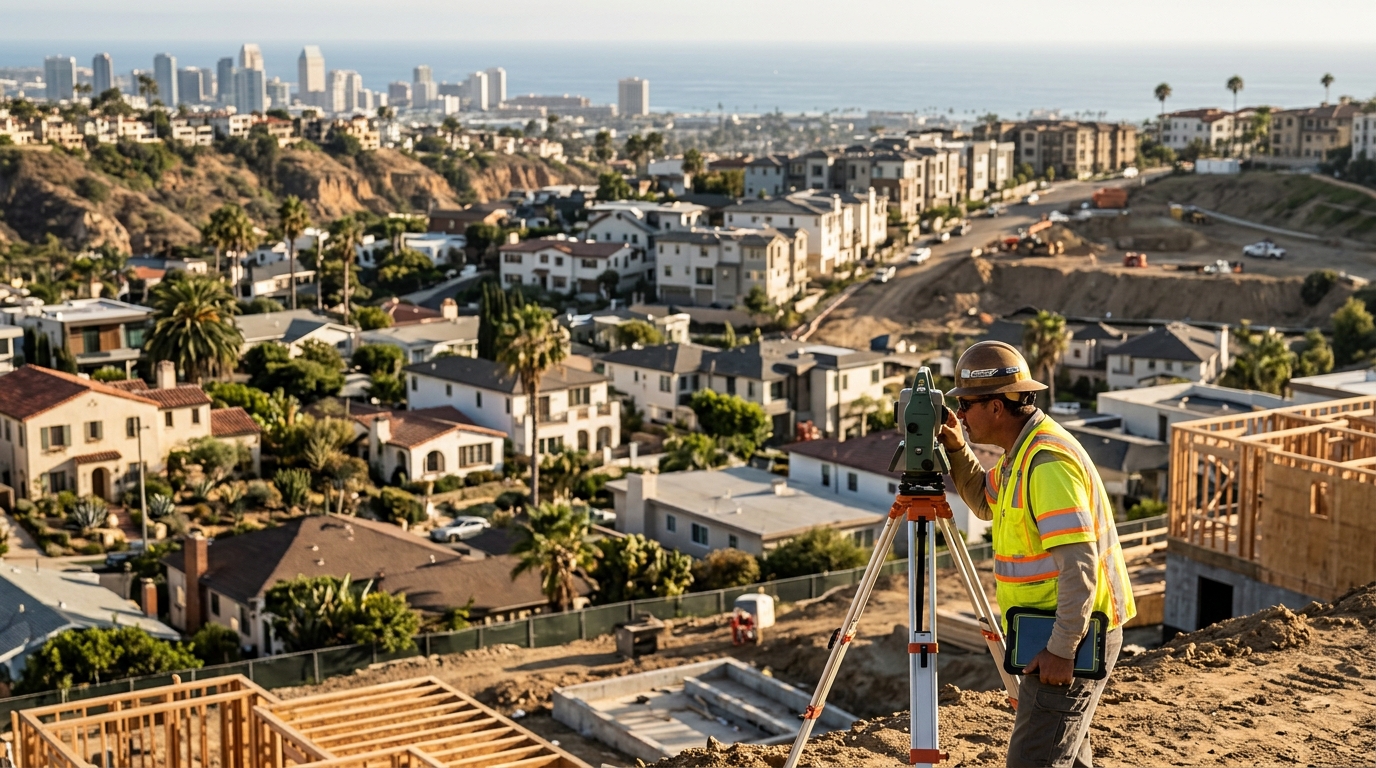
San Diego home prices sit near the top of the national range because the county's supply is physically and legally constrained while demand keeps arriving — but the price you actually face depends far more on which submarket and property type you shop than on any countywide number. Redfin's Southern San Diego median sale price was $782K over the last 3 months, up 0.3% year over year, while the median sale price per square foot there was $531, down 2.4% year over year (Redfin, undated).
Those two numbers moving in opposite directions is the single most useful thing to understand about this market. This guide breaks down what the available data shows, runs the buy-now-versus-wait math on identical loan amounts, and sorts the decision by credit score, down payment and timeline.
What's Actually Happening
Start with the three figures that describe the market rather than the mood.
Price level, countywide-ish: the median sale price of a home in Southern San Diego was $782K over the last 3 months, up 0.3% since the same period last year (Redfin, undated). That is a very small annual change on a very large number. Prices are high; by this measure they are not currently climbing fast.
Price per square foot: the median sale price per square foot in Southern San Diego is $531, down 2.4% since last year (Redfin, undated). When the median price edges up 0.3% while the per-square-foot figure falls 2.4% over the same period, the usual explanation is mix — a larger share of bigger homes closing, or buyers getting more square footage for the same money. It is not evidence of accelerating appreciation.
Speed of sale: homes in Northeastern San Diego receive 3 offers on average and sell in around 23 days (Redfin, undated). Multiple offers and a sub-month sale window tell you well-priced listings still clear quickly in that submarket; they do not tell you anything about an overpriced listing, a dated condo, or a different part of the county.
Submarket spread: the median sale price in Northeastern San Diego was $1.1M last month, down 0.41% since last year (Redfin, undated), while the median sale price for all home types in zip code 92113 was $655,000, up 0.8% year over year (Redfin, November 2025). That is a gap of roughly $445,000 between two parts of the same county. Treat the $1.1M and the $655,000 as separate markets with separate inventory, separate buyer pools and separate negotiation dynamics.
Two honesty notes. First, the Redfin figures above other than the 92113 reading carry no collection date in the source used here — pull the current reading on Redfin or from your agent's MLS export before you price an offer. Second, the structural reasons San Diego prices sit high are well understood and unquantified in this guide: the county is bounded by ocean, an international border, military installations and terrain; buildable land is limited; and local zoning and permitting rules govern how much new supply, of what type, gets approved and where. Those constraints vary city by city and parcel by parcel within the county.
This guide does not forecast the San Diego median sale price or any mortgage rate. Nobody can tell you where either sits in six months.
Buy Now vs. Wait: How It Plays Out
Below, both columns use the same starting point: a $782,000 purchase price — Southern San Diego's median sale price over the last 3 months (Redfin, undated) — with 20% down ($156,400) and a $625,600 loan on a 30-year fixed.
The rates shown are illustrative assumptions for arithmetic only, not quoted market rates and not a prediction. Your actual rate depends on credit score, down payment, loan type (conventional, FHA, VA or jumbo), property type and the lender's pricing on the day you lock.
| Scenario | Price / loan amount | Illustrative 30-yr fixed rate | Monthly principal & interest |
|---|---|---|---|
| Buy now | $782,000 / $625,600 | 6.50% (assumed) | about $3,954 |
| Wait, rate falls 1 point, price flat | $782,000 / $625,600 | 5.50% (assumed) | about $3,552 |
| Wait, rate falls 1 point, price up 3% | $805,460 / $644,368 | 5.50% (assumed) | about $3,658 |
| Wait, rate rises 0.5 point, price flat | $782,000 / $625,600 | 7.00% (assumed) | about $4,162 |
What the arithmetic shows:
- A full 1-point rate drop on this loan size is worth roughly $402 a month in principal and interest. That is the prize for waiting.
- A 3% price increase while you wait eats about $106 a month of that $402 back, leaving roughly $296.
- A 0.5-point rate increase costs about $208 a month against buying today. The downside of waiting is real and symmetrical.
- None of these rows include property taxes, homeowners insurance, HOA dues on a condo or planned development, special assessments such as Mello-Roos districts in some newer San Diego County developments, or mortgage insurance if you put down less than 20%. Those line items vary by property and can move the comparison by hundreds of dollars.
The waiting case is strongest for people who do not have 20% saved yet, because more down payment shrinks the loan in both columns. The waiting case is weakest for anyone in a submarket like Northeastern San Diego, where homes are seeing 3 offers and selling in around 23 days (Redfin, undated) — in that pattern, more of the risk sits in competition for a scarce listing than in the rate.
What To Do Based on Your Situation
- If you are shopping under $700,000: anchor on zip code 92113's $655,000 median for all home types, up 0.8% year over year (Redfin, November 2025), rather than the $782K Southern San Diego figure — the two are different geographies and different time windows. Ask your agent for sold comps restricted to your target zips, property type and bed count from the last 90 days.
- If your credit score is below the mid-600s: get written quotes on both FHA and conventional before you shop. Loan type changes your rate, mortgage insurance and down payment minimum, and on the $625,600 loan modeled above, a 1-point rate difference was worth about $402 a month. Nobody can tell you in advance which program you will be approved for or at what rate.
- If your down payment is under 10%: run the numbers on a smaller unit rather than a larger one. Price per square foot in Southern San Diego was $531, down 2.4% year over year (Redfin, undated), which means the per-foot cost of trading down is currently less punishing than the median price alone suggests.
- If you plan to move again within three to five years: be cautious. Southern San Diego's median rose 0.3% year over year and Northeastern San Diego's fell 0.41% year over year over roughly comparable annual windows (Redfin, undated). With changes that small, agent commission, closing costs and transfer costs dominate a short holding period.
- If your timeline is five-plus years and you have 20% down: focus on the payment you can carry at today's quoted rate, not the rate you hope to refinance into. Use the $3,954 row in the table as the shape of the math, then substitute your real quote.
- If you are competing in a fast submarket: Northeastern San Diego listings average 3 offers and around 23 days on market (Redfin, undated). Have full underwriting done before you offer, and decide your walk-away number in writing before the first counter.
- In every case: an automated estimate from any portal is not an appraised or market value. Have a licensed San Diego agent price the specific property, and take tax and title questions to a California attorney or tax professional.
Frequently asked questions
Why is the median price up but price per square foot down?
Over the same period, Southern San Diego's median sale price was $782K, up 0.3% year over year, while median price per square foot was $531, down 2.4% year over year (Redfin, undated). That combination usually reflects a mix shift — more large homes closing — rather than broad appreciation. Check both metrics for your specific zip and property type before concluding anything about your target home.
Is any part of San Diego meaningfully cheaper?
Yes. Zip code 92113's median sale price for all home types was $655,000, up 0.8% year over year (Redfin, November 2025), against $1.1M in Northeastern San Diego last month, down 0.41% year over year (Redfin, undated). Note the time windows differ — one is a November 2025 reading, the other a single undated month — so treat the roughly $445,000 gap as indicative, not precise.
How fast are San Diego homes selling?
In Northeastern San Diego, homes receive 3 offers on average and sell in around 23 days (Redfin, undated). That figure covers that submarket only. Condos, properties with HOA or Mello-Roos complications, and homes priced above recent comps can take considerably longer in the same zip.
If mortgage rates drop, do I save enough to justify waiting?
On a $625,600 loan (20% down on the $782,000 Southern San Diego median, Redfin, undated), a drop from an assumed 6.50% to an assumed 5.50% on a 30-year fixed is worth about $402 a month in principal and interest. A 3% price increase in the meantime claws back about $106 of that. Those rates are illustrative assumptions, not forecasts or quotes.
How much cash do I need at the $782K median?
A 20% down payment on $782,000 is $156,400, leaving a $625,600 loan (price from Redfin, undated). Below 20% down on a conventional loan you will typically carry private mortgage insurance; FHA loans carry their own mortgage insurance premium. Ask each lender to quote the monthly premium in dollars alongside the rate.
Do national housing headlines apply here?
Not directly. A national median or national rate average describes the country, not San Diego County, and within the county Southern San Diego ($782K median, up 0.3% year over year) and Northeastern San Diego ($1.1M median, down 0.41% year over year) moved in opposite directions (Redfin, undated). Always check which geography and which time window a figure covers before applying it to your offer.
Sources
Written by
Maren Vickery
Maren shapes the publication's voice on housing markets and neighborhood change. She's drawn to the gap between how listings describe a place and how it actually feels to live there. Her editing favors plain language over jargon.