What Is My Home Worth? How to Get an Accurate Value Without Overpaying for an Appraisal
Online estimates, agent CMAs and licensed appraisals miss by different amounts and cost very different money — here's how to choose between them.
By Tobias Lindqvist · Oct 06, 2026 · 9 min read
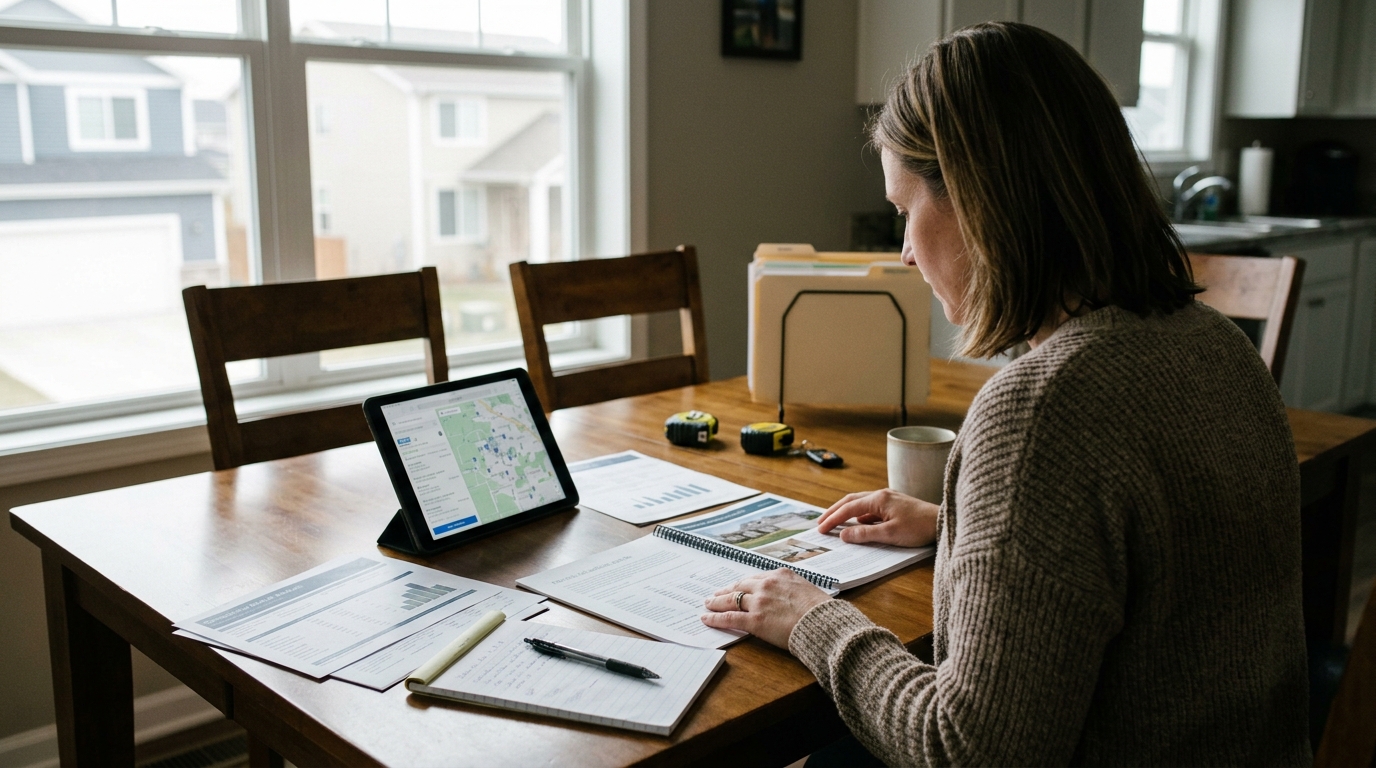
There are three practical ways to put a number on a house: a free online automated valuation model (AVM), a comparative market analysis (CMA) from a real estate agent, and a licensed appraisal. They cost between nothing and a few hundred dollars, take between seconds and a few weeks, and disagree with each other more than most owners expect.
This guide compares them on published cost, turnaround and error figures, shows the order to use them in, and lists the features that push a valuation up or down. Which one you actually need depends on why you need the number — a lender-ordered appraisal and a listing-price estimate are not the same job.
Ways to Find Your Home's Value, Compared
Each method answers a different question. An AVM tells you roughly where a property sits in a statistical model. A CMA tells you what an agent thinks it would list and sell for in your submarket today. An appraisal is a formal opinion of value prepared by a licensed appraiser under USPAP standards, which a lender can lend against (Opendoor, 2025).
| Method | Published cost | Typical turnaround | Published accuracy |
|---|---|---|---|
| Zillow Zestimate (AVM) | Free | Instant | Nationwide median error 1.94% on-market, 7.06% off-market (ListWithClever, 2025); 2.4% on-market and 7.49% off-market as of 2024 (KDS Home Buyers, 2024) |
| Redfin Estimate (AVM) | Free | Instant | Median error roughly 2.1% on-market and 6.45% off-market (Homerise, 2025) |
| Agent CMA | Usually free; some agents charge $100-$200 (HomeLight, 2025) | Same-day to 48 hours (Opendoor, 2025) | No published error rate; non-binding, and the agent is not a licensed valuator (Opendoor, 2025) |
| Desktop appraisal | $82-$218 (Homeyou, 2026) | Remote; no physical inspection (Homeyou, 2026) | Licensed appraiser, but based on public records and online data only (Homeyou, 2026) |
| Full appraisal | Average $358, most pay $314-$423 (HomeAdvisor, 2025); $350-$550 depending on home type and location (Mortgage Research Center, November 2024) | Average seven to 10 days from scheduling to report (HomeAdvisor, 2025); one to two weeks from lender order, up to a month in a busy market (Opendoor, May 2026) | Must use at least three closed sales from the past 12 months from the same market area under Fannie Mae guidelines (Homebuyer.com, 2025) |
Three things to read out of that table.
- The published AVM error rates are nationwide medians, not your metro's. A model trained on plentiful, similar tract housing behaves differently from one trying to price a 1920s bungalow, a rural acreage, or a condo in a building with unusual HOA rules. Zillow's own figures separate on-market from off-market for this reason: 1.94% versus 7.06% (ListWithClever, 2025).
- "Median error" means half of estimates are off by more than that. On an off-market home, a 7.06% median error (ListWithClever, 2025) means a meaningful share of homes are off by far more.
- Appraisal cost quotes differ by source and loan type. HomeAdvisor reports an average of $358 (2025); a standard single-family residential appraisal for a purchase or refinance is reported at $315 to $601, average $359 (Homeyou, 2026); and FHA appraisals run $400 to $700 (Mortgage Research Center, November 2024, citing HomeGuide). HomeAdvisor also gives a rule of thumb of 0.15% to 0.30% of property value (2025) — on a $400,000 home that implies $600 to $1,200, higher than the same source's $358 average, so treat the percentage as an upper-end guideline for larger or complex properties rather than a quote.
How to Get an Accurate Value Estimate
- Pull your own comps first. Find at least three closed sales — not active listings — from the past 12 months in your market area, which is the minimum an appraiser must use under Fannie Mae guidelines (Homebuyer.com, 2025). Most agents prefer comps three months old or less, though six months or more is acceptable for rural or unique properties (HomeLight, 2025). Try to bracket: at least one comp priced above your estimate and one below it (JVM Lending, 2025).
- Run two or three AVMs and write down the spread, not the midpoint. Record the Zestimate and the Redfin Estimate on the same day. If they are $30,000 apart on a $400,000 home, that is a 7.5% gap — consistent with off-market median errors of 7.06% (ListWithClever, 2025) and 6.45% (Homerise, 2025). Treat the spread as your margin of uncertainty.
- Request a CMA from one or two local agents and ask for the worksheet. Most are free with a same-day to 48-hour turnaround (Opendoor, 2025). Ask for the comp addresses, sale dates and the dollar adjustments made for each difference.
What to ask for
"Can you send the CMA with the comp list attached — addresses, close dates, and the adjustments you made for square footage, condition and lot? I'd like to see at least one comp above and one below your number."
- Walk the house the way an appraiser will. An on-site visit usually takes roughly 30 minutes for a standard single-family home (Redfin, 2025). Measure finished square footage, count bedrooms and full and half baths, and note roof age, HVAC age, deferred maintenance and anything permitted or unpermitted. Unpermitted finished space is often excluded.
- Order an appraisal only when the number has to hold up to someone else. For a mortgage, the lender orders it — appraisals are a required part of the process for buyers using a mortgage (HomeLight, 2025), typically costing $350 to $500 (HomeLight, 2025). For a divorce, estate, tax appeal or FSBO price, you can order one privately. Budget seven to 10 days from scheduling to report (HomeAdvisor, 2025) and build in slack: FHA and VA appraisals can take an extra one to two weeks versus conventional, because of finding a qualified appraiser, longer reports, and required repairs (Redfin, 2025).
- Ask your lender whether a desktop appraisal is allowed. A desktop appraisal is a remote valuation from public records and online data with no physical inspection, typically $82 to $218 (Homeyou, 2026). Eligibility is set by the lender and loan program, not by you.
- Finish with a range. State your conclusion as a band — for example $385,000 to $415,000 on a $400,000 estimate — and say which comp drives each end. None of this guarantees a sale price, a closing date or how long the home sits on the market.
For a specific transaction, confirm your conclusions with a licensed agent, appraiser, attorney or tax professional in your state.
Features That Raise or Lower Your Home's Value
No published dollar or percentage figure is cited below, because the effect of any single feature depends on the metro, the submarket, the property type and what the comps show. Each row is a general direction only — appraisers quantify it by comparing paired sales in your market, not by applying a national rule.
| Feature or condition | Direction | How the value is actually set |
|---|---|---|
| Additional finished above-grade square footage | Generally up | Adjusted per square foot using local paired sales; must be permitted and heated |
| Finished basement | Generally up, but less per square foot than above-grade space | Usually reported separately from gross living area; treatment varies by state and by appraiser convention |
| Extra full bathroom | Generally up | Adjusted as a line item against comps with the same bed count |
| Roof, HVAC or water heater at end of life | Generally down | Appraisers may note condition; FHA and VA appraisals can require repairs before closing (Redfin, 2025) |
| Unpermitted addition or converted garage | Varies; often excluded entirely | Often not counted in finished square footage without permits; check local permitting rules |
| Dated kitchen or bathrooms versus comps | Generally down relative to updated comps | A condition adjustment, not a guaranteed return on any renovation spend |
| Busy road, rail line or commercial frontage | Generally down | External obsolescence adjustment, measured against comps on quieter streets |
| Large or irregular lot | Varies | Depends on local zoning and whether the lot is subdividable |
| Pool | Varies sharply by climate and metro | A plus in some markets, a maintenance liability in others; the comps decide |
| High HOA dues or special assessment (condo) | Generally down | Buyers price monthly cost; pending assessments and reserve shortfalls matter |
| Attached school attendance zone | Varies | Only cite a specific district or school rating with the dataset and year it came from; do not assume from reputation |
| Solar panels | Varies by ownership | Owned systems are treated differently from leased systems, which transfer as an obligation |
| Active permits, liens or title defects | Generally down or blocking | May need to clear before a lender will fund |
If you are deciding what to fix before listing, ask your agent which of these items appear as adjustments in your actual comp set. A feature with no comp support in your submarket is unlikely to show up in a valuation, however much it cost to install.
Frequently asked questions
Why is my Zestimate different from my agent's CMA?
They are built differently. The Zestimate is a statistical model with a nationwide median error rate of 1.94% for on-market homes and 7.06% for off-market homes (ListWithClever, 2025); Redfin's estimator reports roughly 2.1% on-market and 6.45% off-market (Homerise, 2025). A CMA is a human judgment from an agent who has seen comparable interiors, is non-binding, and is prepared by someone who is not a licensed valuator (Opendoor, 2025). Neither equals an appraised value.
How much does an appraisal cost, and how long does it take?
HomeAdvisor reports a nationwide average of $358, with most homeowners paying $314 to $423 (2025), and an average of seven to 10 days from scheduling to final report (2025). Other sources report $350 to $550 depending on home type and location (Mortgage Research Center, November 2024) and $400 to $700 for FHA appraisals (Mortgage Research Center, November 2024, citing HomeGuide). From the moment a lender orders it, allow one to two weeks, or up to a month in a busy market (Opendoor, May 2026).
How recent do comparable sales need to be?
Under Fannie Mae appraisal guidelines, appraisers must use at least three closed sales from the past 12 months, from the same market area and with similar characteristics (Homebuyer.com, 2025). Most agents prefer comps three months old or less, though six months or more is acceptable for rural or unique properties (HomeLight, 2025). Valid comps should bracket your number — at least one higher and one lower (JVM Lending, 2025).
Is there a cheaper alternative to a full appraisal?
A desktop appraisal is a remote valuation based on public records and online data with no physical inspection, typically $82 to $218 (Homeyou, 2026). Whether one is acceptable is decided by your lender and loan program, not by you. For a purchase mortgage, an appraisal is a required part of the process (HomeLight, 2025), so ask the lender first rather than ordering anything yourself.
Sources
- ListWithClever — Zillow Zestimate Accuracy: How Reliable Is It in 2025? (2025)
- KDS Home Buyers — Are Zillow Zestimates Accurate? What Sellers Should Know (2024)
- Homerise — Is Zillow Zestimate Accurate? (The Truth About the 7.5% Gap) (2025)
- HomeAdvisor — How Much Does a Home Appraisal Cost in 2025? (2025)
- Mortgage Research Center (mortgageresearch.com) — How Much Does a Home Appraisal Cost in 2026? (2024-11)
- Opendoor — Comparative Market Analysis (CMA): What It Is and How Agents Run One (2025)
- HomeLight — How Much Does a Comparative Market Analysis Cost, and Is It Ever Free? (2025)
- Redfin — How Long Does an Appraisal Take? (2025)
- Opendoor — How long does a home appraisal take? (2026-05-18)
- Homebuyer.com — Fannie Mae Guidelines: Comparable Sales in Appraisals (2025)
- JVM Lending — Comparable Sales Appraisers Can and CAN'T Use (2025)
- HomeLight — How to Price Your Home Right by Using House Comps (2025)
- Homeyou — How Much Does a Home Appraisal Cost in 2026? (2026)
Written by
Tobias Lindqvist
Tobias covers floor plans, renovation trends, and the small design decisions that change how a home works. He's suspicious of trends that promise to 'future-proof' a house. He prefers writing about function over finishes.