Home Valuation 101: What Actually Determines What Your House Is Worth
Three tools, three price tags, three error margins — and the reasons an algorithm, an agent and an appraiser can each land on a different number for the same house.
By Maren Vickery · Oct 06, 2026 · 9 min read
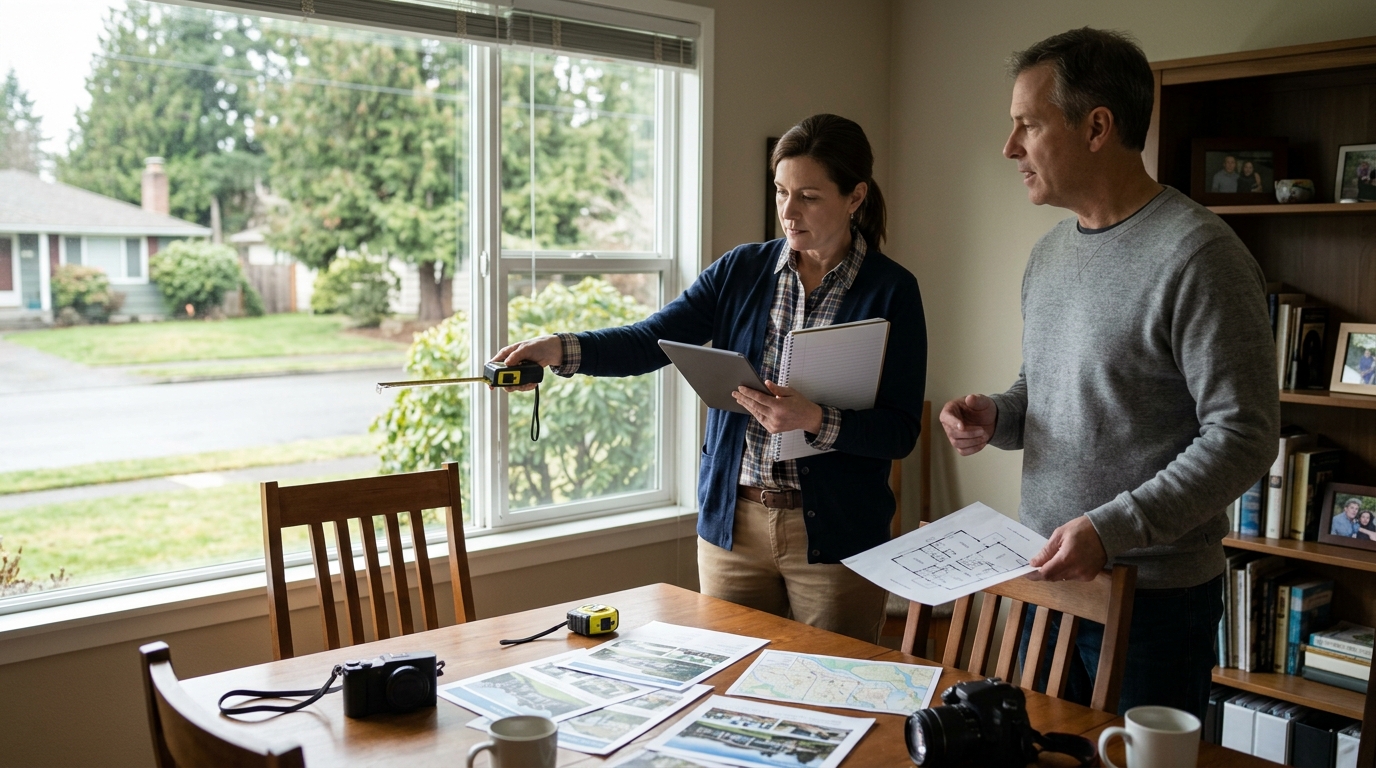
A home's value isn't one number. It's a range produced by whoever is estimating it, using whatever data they can see. An automated estimate reads public records and recent sales; an agent walks the rooms; an appraiser is paid to defend a figure a lender will lend against.
This guide compares the three on cost, turnaround and published accuracy, then walks through how to pull comparable sales yourself and which features tend to move a number up or down.
Ways to Find Your Home's Value, Compared
| Method | Typical cost | Turnaround | Published accuracy | Best for |
|---|---|---|---|---|
| Online AVM (Zestimate, Redfin Estimate) | Free | Instant | Zillow states a 1.9% nationwide median error on-market and 7.0% off-market (Zillow, undated); The Close reports 1.94% and 7.06% (The Close, undated) and Redfin's on-market median error as 1.93% (The Close, undated) | A starting range, tracking a market over time |
| Agent's CMA (comparative market analysis) | Usually free, offered in hopes of winning the listing | A day to about a week | No industry-wide published error rate; accuracy depends on the comps chosen and the agent's local knowledge | Pricing a home you're about to list or offer on |
| Licensed appraisal | $357 average for a single-family home, typically $314–$423, citing 2025 Angi data (Bankrate, 3 March 2025) | Commonly days to a couple of weeks, depending on appraiser availability | No published median error rate; it's an opinion of value supported by written analysis, which is why lenders accept it | Mortgage approval, refinancing, divorce, estate and tax disputes |
On the AVM numbers. Zillow publishes Zestimates for more than 104 million homes (Zillow, undated); List With Clever puts the current figure at 116 million (List With Clever, undated). Scale is the point — and the limit. An algorithm reads tax records, prior sales and listing data. It cannot see that your kitchen was gutted in 2019, that the back bedroom has no closet, or that the house faces a four-lane road.
The gap between the on-market and off-market error rates tells you why. Once a home is listed, the AVM can see the asking price and the photos. Before that, it's working from records alone.
Medians hide the tails. A median error of 7.0% means half of estimates are off by less and half by more. Zillow states that in major metro areas, the on-market Zestimate lands within 20% of the actual selling price more than 99% of the time (Zillow, undated) — which also means some land outside that band. Eaton Realty recounts a Zillow co-founder selling his Seattle home for $1.05 million, roughly 40% below its $1.75 million Zestimate (Eaton Realty, undated).
Accuracy is local. List With Clever reports Zillow's off-market median error at 4.62% in Colorado Springs versus 9.10% in Cleveland (List With Clever, undated), and Own Luxury Homes cites 12.7% in Vermont versus 5.3% in Colorado (Own Luxury Homes, undated). Homerise reports Redfin's claimed figures at about 6.45% off-market and 2.1% on-market against Zillow's 7.5% and 1.9% (Homerise, undated). Different sources quote slightly different numbers because the providers update them; check the provider's own accuracy page for your county before you trust a figure.
Appraisal cost is also local. Angi data cited by Bankrate shows an average of $325 in Cleveland versus $500 in Seattle (Bankrate, 3 March 2025). Federal law requires appraiser pricing to be "reasonable and customary" for the geographic area (Bankrate, 3 March 2025). Condo, multifamily and complex rural properties often cost more than the single-family averages above.
How to Get an Accurate Value Estimate
- Pull your own comps first. Find three to six sold homes — not active listings — within about a mile, closed in the last three to six months, within roughly 20% of your square footage, the same property type (don't compare a condo to a detached house), and ideally the same school attendance zone and HOA. In slow markets or rural areas you may have to stretch to twelve months and a wider radius; note that you did.
- Adjust the comps line by line. Take each comp's sale price and add or subtract for differences: bedroom and bath count, garage spaces, lot size, finished basement, condition of roof and HVAC, and whether it backs onto a busy road. Write the adjustments down. A number you can't explain in a sentence per line isn't a value, it's a guess.
- Check two or three AVMs and record the date. Look up your address on more than one estimator and screenshot the figures. Treat the spread between them as your uncertainty band — and remember the off-market median error is 7.0% nationally (Zillow, undated), which on a $400,000 home is about $28,000 either way.
- Correct your public record. Open the tax assessor's record and the AVM's own "home facts" and fix wrong bedroom counts, square footage or lot size, and add permitted work. AVMs are fed by these records; a house listed as two beds when it has four will be valued as two.
- Request a CMA from two or three local agents who have closed sales in your zip code in the past year. Ask each for the comp list they used and the adjustments they made, not just the suggested price. Ask what their recommended list price assumes about condition and timing.
- Order a licensed appraisal when the number has to hold up. For a mortgage, refinance, appeal, divorce or estate settlement, budget the $314–$423 typical single-family range (Bankrate, 3 March 2025) and expect more for a condo in a complex building or an unusual property. If a lender orders it, you generally can't pick the appraiser.
- Prepare for the walkthrough. Give the agent or appraiser a one-page list of permitted improvements with dates and costs, the age of roof, furnace, water heater and electrical panel, and your HOA dues and what they cover.
- Re-check in 60 to 90 days if you don't act. Comps age out. A set of sales from six months ago describes a different rate environment and a different inventory level than today's.
Features That Raise or Lower Your Home's Value
No published national figure attaches a reliable dollar or percentage impact to most individual features, and the ones that circulate rarely transfer between metros. The effects below are directional and general unless marked otherwise — an appraiser's adjustment for the same feature in your market is the number that counts.
| Feature or condition | Direction | What to know |
|---|---|---|
| Finished basement with permits | Up | General effect. Often valued per square foot below above-grade space; unpermitted finishing may be excluded from the appraisal entirely. |
| Added bedroom or full bathroom (permitted) | Up | General effect. Counts only if it meets local code for egress, ceiling height and ventilation. |
| Roof at or past end of life | Down | General effect. Buyers and some loan programs (notably FHA and VA) may require repair before closing; lenders can condition funding on it. |
| Dated HVAC, water heater or electrical panel | Down | General effect, usually deducted near replacement cost rather than as a percentage. |
| Busy road, rail line or commercial frontage | Down | General effect. Appraisers typically take an "external obsolescence" adjustment using paired sales in the same market. |
| Garage spaces versus comps | Either | General effect. Matters more in cold or car-dependent markets than in dense transit areas. |
| School attendance zone | Either | Do not accept a claim here without a dataset. Check your state education agency's current-year ratings and the district's own attendance boundary map, and cite the year. |
| High or rising HOA dues, or special assessments | Down | General effect. Dues reduce the payment a buyer can afford at a given price; pending assessments and litigation can block condo financing outright. |
| Flood zone, wildfire or coastal exposure | Down | General effect, driven by insurance cost and availability. Check the current FEMA flood map panel for your parcel. |
| Solar panels | Either | General effect. Owned systems are treated differently from leased or PACE-financed ones, which transfer as an obligation to the buyer. |
| Pool | Either | General effect. Can read as an amenity in hot climates and as maintenance and insurance cost elsewhere. |
| Deferred cosmetic condition (paint, flooring, landscaping) | Down | General effect, and usually the cheapest gap to close before listing. |
| Square footage recorded incorrectly | Either | Fixable. An appraiser measures the home; the assessor's record may be years out of date. |
Two cautions. First, no renovation can be promised to pay for itself at resale — recovery varies by market, buyer pool and how recent the work is. Second, zoning and permitting rules decide whether an addition or ADU is even countable in your jurisdiction; check with your local planning department before you budget for the value.
Frequently asked questions
How far off can a Zestimate be on my house?
Zillow states a nationwide median error rate of 1.9% for on-market homes and 7.0% for off-market homes (Zillow, undated). On a $400,000 off-market home, a 7.0% median error is roughly $28,000 — and half of estimates miss by more than the median. Local variation is large: List With Clever reports an off-market median error of 4.62% in Colorado Springs versus 9.10% in Cleveland (List With Clever, undated). Eaton Realty recounts a Zillow co-founder's Seattle home selling for $1.05 million against a $1.75 million Zestimate, about 40% below (Eaton Realty, undated).
What does a home appraisal cost, and who pays?
Citing 2025 Angi data, Bankrate reports an average of $357 for a single-family home, typically $314 to $423 (Bankrate, 3 March 2025). Cost tracks location: $325 average in Cleveland versus $500 in Seattle (Bankrate, 3 March 2025). Federal law requires appraiser fees to be reasonable and customary for the area (Bankrate, 3 March 2025). On a purchase or refinance the lender orders it and the borrower usually pays, often at application or at closing.
Is a free CMA from an agent as good as a paid appraisal?
They answer different questions. A CMA is a pricing opinion aimed at what a buyer will pay now; an appraisal is a licensed, written opinion a lender will underwrite against. There is no industry-wide published error rate for either. If you need a number for a mortgage, refinance, tax appeal, divorce or estate, pay for the appraisal — the $314 to $423 typical range (Bankrate, 3 March 2025) is small next to the amount at stake.
Does a second automated estimate help?
It gives you a spread rather than a single point. The Close reports Redfin's on-market median error at 1.93% against Zillow's 1.94% (The Close, undated), and Homerise reports Redfin at about 6.45% off-market and 2.1% on-market versus Zillow's 7.5% and 1.9% (Homerise, undated). Different sources quote slightly different numbers, so check each provider's own published accuracy page for your county rather than relying on a national average.
Sources
- Zillow — How Accurate Is My Zestimate, and Can I Influence It?
- Bankrate — How Much Does A Home Appraisal Cost? (2025-03-03)
- The Close — Zillow Estimates Guide: What It Is & How Accurate It Is
- List With Clever — Zillow Zestimate Accuracy: How Reliable Is It in 2025?
- Homerise — Is Zillow Zestimate Accurate? (The Truth About The 7.5% Gap)
- Eaton Realty — How Accurate Is Zillow's Zestimate?
- Own Luxury Homes — How Accurate Is Zillow Zestimate 2026
Written by
Maren Vickery
Maren shapes the publication's voice on housing markets and neighborhood change. She's drawn to the gap between how listings describe a place and how it actually feels to live there. Her editing favors plain language over jargon.