Rent vs. Buy: What the Local Math Says Before You Make an Offer
Mortgage rates near 7%, inventory at a decade high, and flat days on market change the rent-versus-buy break-even — but only your metro's figures decide it.
By Priya Natarajan-Wells · Oct 06, 2026 · 10 min read
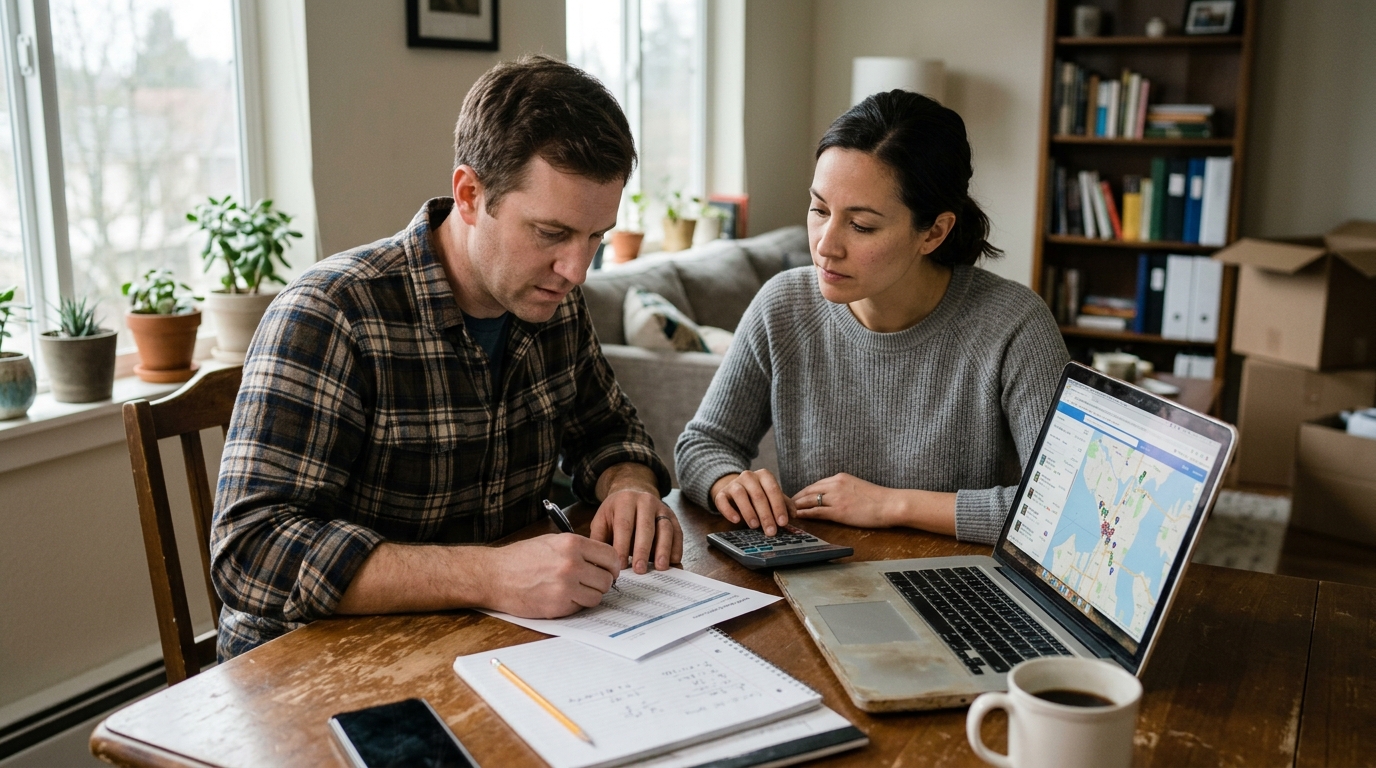
Rent versus buy is not a national question, even though the headlines are national. Whether buying beats renting where you live depends on your metro's prices and inventory, the rate your lender actually quotes you, how long you plan to stay, and what your landlord is asking at renewal.
This guide lays out the most recent national benchmarks — the 30-year fixed rate at 6.95% (Freddie Mac, 2026-09-17), a median existing-home price of $429,100 (NAR, 2026-09-10), and 1.62 million unsold homes (NAR, 2026-09-10) — then shows you which local numbers to pull before you write an offer.
Current Market Conditions
Four numbers drive the rent-versus-buy math: price, financing cost, how much choice you have, and how fast homes move. Here is where each stood most recently at the national level. Treat these as the backdrop, not as your market — the same month can look entirely different in a condo-heavy downtown and a suburb of detached single-family homes 20 miles away.
Price. The median existing-home sales price rose 1.6% year-over-year to $429,100 in August (NAR, 2026-09-10). Redfin's separate national measure put the median sale price at $398,596 in August, up 2.2% year-over-year (Redfin, 2026-08). The two differ because they cover different transaction sets; neither is the value of any particular house, and neither is an appraisal.
Financing cost. The 30-year fixed-rate mortgage averaged 6.95% as of 2026-09-17, up from 6.76% the prior week and 6.26% a year earlier (Freddie Mac). The 15-year fixed averaged 6.26%, up from 6.09% the prior week and 5.41% a year earlier (Freddie Mac, 2026-09-17). Those are survey averages for conventional conforming loans. Your quoted rate will differ with loan type — FHA, VA, and jumbo price separately — and with credit score, down payment, and whether the property is a condo with a non-warrantable HOA.
Inventory. Unsold inventory rose 3.2% month-over-month to 1.62 million units, a 4.9-month supply and the highest level in over a decade (NAR, 2026-09-10). Redfin counted 1,534,918 homes for sale nationally, up 2.7% year-over-year, with 393,178 newly listed, up 4.3% (Redfin, 2026-08).
Speed. The median home sat on the market 50 days nationally in August, unchanged from a year earlier (Redfin, 2026-08). Existing-home sales ran at a seasonally adjusted annual rate of 3.98 million in August, down 2.0% from July and 1.2% year-over-year (NAR, 2026-09-10).
On the demand side, NAR Chief Economist Lawrence Yun noted wages grew 3.1% in August and 643,000 net new jobs had been added since the start of the year, supporting homebuying demand despite higher rates (NAR, 2026-09-10).
Market Data at a Glance
| Metric | Latest reading | Year-over-year change | Source and date |
|---|---|---|---|
| Median existing-home sale price | $429,100 | +1.6% | NAR, 2026-09-10 |
| Median sale price (separate measure) | $398,596 | +2.2% | Redfin, 2026-08 |
| Existing-home sales pace | 3.98 million SAAR | −1.2% | NAR, 2026-09-10 |
| Homes sold | 291,769 | −0.45% | Redfin, 2026-08 |
| Homes for sale | 1,534,918 | +2.7% | Redfin, 2026-08 |
| Unsold inventory | 1.62 million units (4.9-month supply) | +3.2% month-over-month, highest in over a decade | NAR, 2026-09-10 |
| Newly listed homes | 393,178 | +4.3% | Redfin, 2026-08 |
| Median days on market | 50 days | Unchanged (0 days) | Redfin, 2026-08 |
| Months of supply | 4 months | Unchanged (0 months) | Redfin, 2026-08 |
| 30-year fixed mortgage rate | 6.95% | Up from 6.26% a year earlier | Freddie Mac, 2026-09-17 |
| 15-year fixed mortgage rate | 6.26% | Up from 5.41% a year earlier | Freddie Mac, 2026-09-17 |
| 30-year rate (separate tracker) | 6.7% | +0.08 percentage points | Redfin, 2026-08 |
| U.S. National Home Price Index | +1.3% year-over-year; −0.3% month-over-month, pre-seasonal adjustment | Down from +1.6% the prior month | S&P Case-Shiller via Calculated Risk, 2025-11 |
Every row above is national. Pull the same rows for your own metro before you decide anything — a market with rising months of supply and a market with two weeks of inventory produce opposite negotiating positions from the same national headline.
Signals Worth Watching
These are things you can check yourself, weekly or monthly, without a subscription or an agent's login.
- The weekly Freddie Mac Primary Mortgage Market Survey. Published every Thursday on Freddie Mac's site. The 30-year fixed moved from 6.76% to 6.95% in a single week to 2026-09-17, and sat at 6.26% a year earlier. Watching it tells you whether your lender's quote is tracking the market or lagging it.
- New listing volume in your metro. Nationally, 393,178 homes were newly listed in August, up 4.3% year-over-year (Redfin, 2026-08). Redfin's Data Center and your local MLS's public-facing market reports break this out by metro and often by ZIP code. Rising new listings in the submarket you want means more choice; falling ones mean competition.
- Months of supply for your property type. The national figure was 4.9 months (NAR, 2026-09-10) and 4 months on Redfin's measure (Redfin, 2026-08). Condos and single-family homes in the same city frequently differ by months. Local Realtor association monthly reports publish this split.
- Median days on market in your target neighborhood versus the national 50 days (Redfin, 2026-08). If local homes are going under contract in under two weeks, plan for escalation clauses and fast inspections. If they are sitting past 50 days, price reductions and seller credits become realistic asks.
- Price-index direction, not just the level. The S&P/Case-Shiller U.S. National Index rose 1.3% year-over-year but fell 0.3% month-over-month on a pre-seasonally-adjusted basis, with the 10-City and 20-City Composites each down 0.5% (S&P Case-Shiller via Calculated Risk, 2025-11). If your metro is in the 20-City Composite, that release gives you a metro-level line.
- Local employment and wage data. NAR cited 3.1% August wage growth and 643,000 net new jobs added since the start of the year as supporting demand (NAR, 2026-09-10). Your state workforce agency publishes metro-level payroll data monthly; a single large employer's announcement moves some submarkets more than any national number.
- Your own renewal letter. The rent side of the equation is a document you already receive. Compare the renewal figure in writing against a lender's Loan Estimate — specifically the projected payments table on page 1 and the total closing costs on page 2 — for a home at your target price.
Bottom Line for Buyers
Given that unsold inventory reached 1.62 million units and a 4.9-month supply as of 2026-09-10 (NAR) — the highest in over a decade — and that median days on market held at 50 nationally in August (Redfin, 2026-08), buyers in markets showing the same pattern have more negotiating room than they did when supply was tighter. That matters more than the headline price: at a 4.9-month supply, repair credits, rate buydowns, and appraisal-gap protections are things you can ask for rather than things you have to waive.
That is conditioned on your market matching those figures. If your metro's months of supply is under two and local days on market is well below 50, none of the above applies to you, and the national inventory story will not help your offer.
On rates: the 30-year fixed moved 0.19 percentage points in one week to 6.95% (Freddie Mac, 2026-09-17) and is 0.69 points above the 6.26% of a year earlier. Nobody can tell you where it goes next. What you can do is run the comparison at the rate you are actually quoted on your Loan Estimate, not at a survey average.
On prices: the national median existing-home price was still up 1.6% year-over-year at $429,100 (NAR, 2026-09-10), while the Case-Shiller National Index fell 0.3% month-over-month pre-seasonal adjustment (S&P Case-Shiller via Calculated Risk, 2025-11). Those two can both be true. Waiting for a decline that your specific submarket may not deliver has a cost: the rent you pay in the meantime.
A practical sequence:
- Get a preapproval with a lender, submitting the Uniform Residential Loan Application (Form 1003) along with two most recent W-2s, 30 days of pay stubs, two months of bank statements, and a signed gift letter if any down payment funds come from family.
- Ask for a written Loan Estimate at your target price so you have real numbers for principal, interest, taxes, insurance, mortgage insurance, and HOA dues.
- Pull your metro's median sale price, months of supply, and median days on market from your local MLS or Realtor association report for the most recent month.
- Compare the all-in monthly figure against your renewal rent, then against how long you expect to stay — closing costs on the Loan Estimate and the agent commissions and transfer taxes on the eventual seller's side are what a short stay fails to recover.
- Have a licensed agent, and in attorney-closing states a real estate attorney, review your contract terms; the escrow officer or title company will handle the settlement statement and title commitment, and you should read both.
Nothing here is advice on your transaction. State disclosure law, transfer taxes, HOA resale packages, and permitting rules vary enough that a local agent, attorney, and tax professional are the only people who can price your specific decision.
Frequently asked questions
Should I lock my rate now or float?
The 30-year fixed moved from 6.76% to 6.95% in one week, ending 2026-09-17 (Freddie Mac) — 0.19 percentage points in seven days. If a move that size would break your budget, lock. Ask your loan officer in writing for the lock length (30, 45, or 60 days), the extension fee if your closing slips, and whether a float-down is available. Lock expiration dates are tied to your contract's closing date, so align them before you sign.
Is it worth waiting for prices to fall?
The national median existing-home price rose 1.6% year-over-year to $429,100 in August (NAR, 2026-09-10), while the S&P/Case-Shiller National Index fell 0.3% month-over-month pre-seasonal adjustment (via Calculated Risk, 2025-11). Direction differs by metro and by month. Nobody can tell you where prices go next, and while you wait you pay rent. Decide on your own metro's most recent monthly MLS report, not the national line.
How likely am I to face a bidding war?
With a 4.9-month national supply (NAR, 2026-09-10) and a median 50 days on market (Redfin, 2026-08), the national picture is not a bidding-war market. But those are averages across every price band and property type. Check days on market for your price range and neighborhood in your local MLS report: under roughly two weeks means prepare for escalation terms; near or past 50 days means price reductions are common.
How long do I need to stay for buying to beat renting?
Long enough to recover your closing costs. Use the Total Closing Costs figure on page 2 of your Loan Estimate, add the transfer taxes and agent commissions you would pay when selling, and divide by the monthly gap between your rent and your all-in ownership payment. With the 30-year fixed at 6.95% (Freddie Mac, 2026-09-17), early payments are heavily interest, so principal builds slowly. Do not assume any future appreciation in the calculation.
Would a 15-year loan change the comparison?
It changes the rate but raises the payment. The 15-year fixed averaged 6.26% versus 6.95% for the 30-year as of 2026-09-17 (Freddie Mac) — a 0.69-point difference. The shorter term means a materially higher monthly payment, which can push the ownership cost further above your rent in the near term. Ask your lender for Loan Estimates on both terms and compare the projected payments tables side by side.
Sources
- Freddie Mac — Mortgage Rates Average 6.95% (2026-09-17)
- National Association of Realtors (NAR) — NAR Existing-Home Sales Report Shows 2.0% Decrease in August (2026-09-10)
- Redfin — United States Housing Market & Prices (2026-08)
- S&P Case-Shiller (via Calculated Risk) — Case-Shiller: National House Price Index Up 1.3% year-over-year in September (2025-11)
Written by
Priya Natarajan-Wells
Priya writes about first-time buyers and the emotional math of mortgages. She likes tracing how a single rate change ripples through an ordinary family's plans. Her pieces tend to start with a kitchen table, not a spreadsheet.