Refinancing Step-by-Step: What It Costs and How Long It Takes
Where the money actually goes — lender charges, title and escrow, appraisal, prepaids — and which of those you can shop for, push back on, or skip.
By Odalys Reyes Fontaine · Oct 06, 2026 · 10 min read
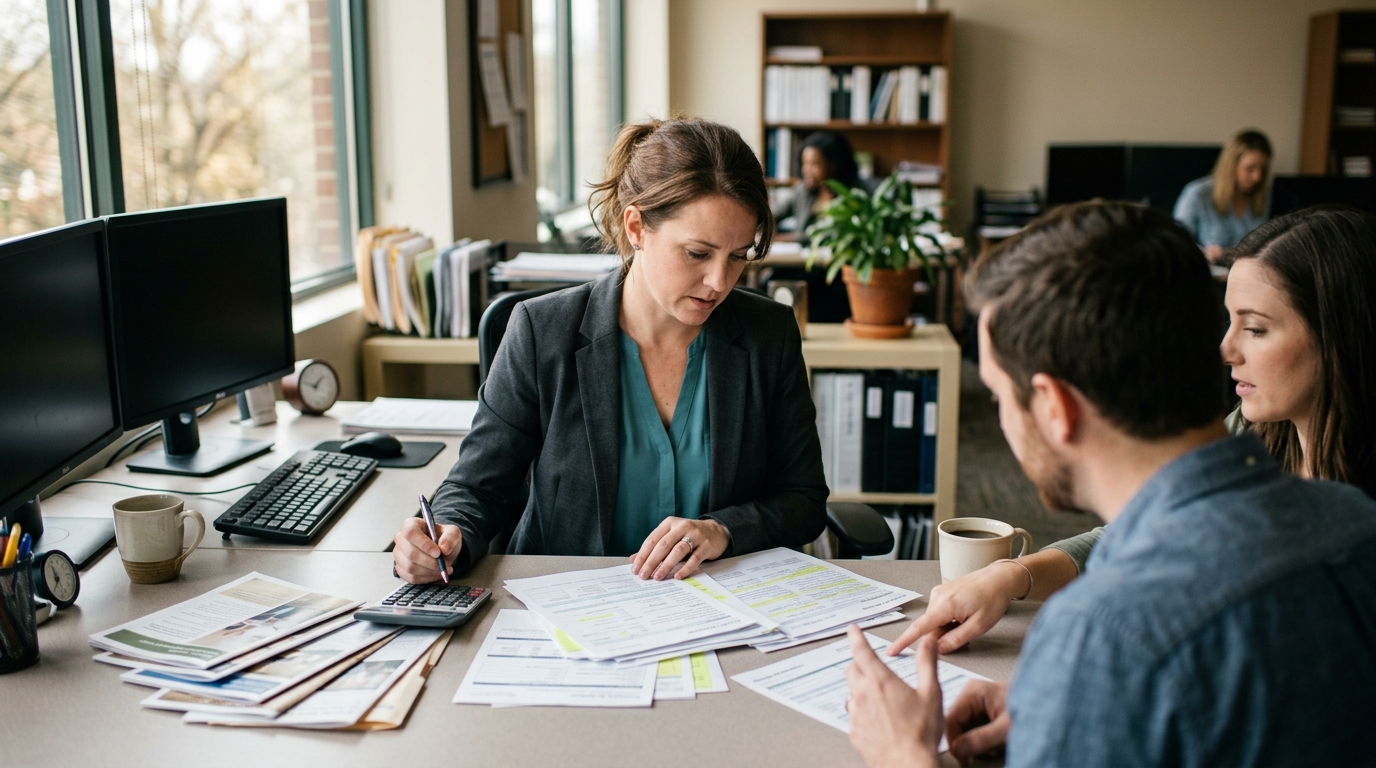
A refinance is a new mortgage on a home you already own: you apply, a lender underwrites you again, a settlement agent pays off the old loan, and you start making payments on the new one. The work is mostly paperwork, and the cost is mostly a stack of separate fees — some set by the lender, some by the title company, some by your county or state.
One thing to be straight about: the only numbers that apply to your refinance are the ones on your own Loan Estimate and Closing Disclosure, for your metro, your property type and your loan program. Below, where a dollar figure or a day-count belongs, this guide names the source that publishes one and tells you where on your paperwork to read your own — rather than quoting a figure that may not be current, local, or yours.
Cost Breakdown
Refinance costs fall into five groups. On your Loan Estimate they appear in lettered sections, which is the fastest way to tell a lender charge from a third-party charge from a government charge.
Lender charges (loan origination, application and underwriting, credit report). Mortgage.com's sample itemized refinance breakdown lists a loan origination fee, an application/underwriting fee, and a credit report fee as separate lines (Mortgage.com, undated); Benzinga's list of average refinance fees names an application fee and a loan origination fee as well (Benzinga, undated). Origination is often quoted as a percentage of the loan amount, so it scales with how much you borrow. These sit in section A of the Loan Estimate and are the most negotiable part of the file — ask for them in writing from two or three lenders on the same day, because they move with rates.
Appraisal. Houzeo publishes a refinance appraisal cost range for a single-family home (Houzeo, undated); condos, multifamily and rural properties price differently, and a complex or high-value property costs more. Some streamline programs waive the appraisal entirely. You usually pay this one up front, outside closing, and it is non-refundable once the appraiser has been out.
Title insurance, title search and settlement/closing fees. This is the line that swings hardest by state. Federal Title & Escrow Company, which handles closings in DC, Maryland and Virginia, publishes an all-inclusive settlement fee for refinance closings and a minimum lender's title insurance premium for a refinance policy (Federal Title & Escrow Company, undated) — a useful illustration of how a DC-area file is priced, and not a figure you should expect in Texas or California. Benzinga lists title insurance and search, plus attorney fees, among standard refinance charges (Benzinga, undated); attorney involvement is required in some states and optional in others. You are refinancing a property you already own, so ask about a reissue or substitution rate on the lender's title policy.
Recording and government charges. Mortgage.com's sample breakdown includes title and recording fees (Mortgage.com, undated). Recording is set by your county, and some states and cities add mortgage recording or transfer taxes on a refinance. These are not negotiable with anyone.
Prepaids, escrow and optional points. Mortgage.com's example also includes prepaid taxes and interest (Mortgage.com, undated). These are not a cost of refinancing so much as money you would owe anyway, moved forward; your old escrow account is usually refunded separately after payoff. Separately, you can buy mortgage discount points to lower your refinance interest rate, priced as a share of the loan amount (CBS News, undated). Two warnings: if you bought recently, check your current note for a prepayment penalty — CBS News cites a penalty range for borrowers who refinance too soon after buying (CBS News, undated) — and compare offers on both the interest rate, which sets your monthly payment, and the APR, which folds lender fees and points into a single annualized figure. Two loans with the same interest rate can have very different APRs. Freddie Mac's weekly Primary Mortgage Market Survey (Freddie Mac, 2026-10-01) publishes an average 30-year fixed interest rate, not an APR, and not an offer to you.
For a total, Freddie Mac's estimate of the average cost to refinance a mortgage (Freddie Mac, via CBS News, undated) is a starting benchmark. Your number comes from page 2 of your Loan Estimate.
Itemized Costs by Category
| Fee | Who sets it | Negotiable? | Where the published range comes from |
|---|---|---|---|
| Loan origination fee | Lender | Yes — shop it and ask for a credit | Listed as a line item in Mortgage.com's sample refinance breakdown and in Benzinga's list of average refinance fees |
| Application / underwriting fee | Lender | Yes — often waived to win the loan | Mortgage.com's itemized example; Benzinga lists an application fee |
| Credit report fee | Lender (passed through from the bureau) | No — fixed pass-through | Mortgage.com's itemized example |
| Appraisal fee | Appraiser / appraisal management company | No, but may be waived on streamline programs | Houzeo publishes a refinance appraisal range for a single-family home |
| Lender's title insurance premium | Title underwriter, filed by state | Sometimes — ask for a reissue/refinance rate | Federal Title & Escrow publishes a minimum refinance lender's policy premium for DC, Maryland and Virginia |
| Title search and settlement/closing fee | Title or escrow company | Yes — you may choose your own provider in most states | Federal Title & Escrow publishes an all-inclusive refinance settlement fee for DC, Maryland and Virginia |
| Attorney fee | Attorney; required in some states | Yes where optional; set by firm where required | Benzinga lists attorney fees among average refinance fees |
| Recording fee and any transfer/mortgage tax | County or state | No | Mortgage.com's example includes title and recording fees |
| Prepaid interest, taxes and insurance | Calendar and your taxing authority | No — but the amount shifts with your closing date | Mortgage.com's example includes prepaid taxes and interest |
| Discount points (optional) | You, by choice | Yes — buy, reduce or skip | CBS News describes points as a share of the loan amount paid to lower the rate |
| Prepayment penalty on the loan being paid off (if any) | Your existing note | No — read the note | CBS News cites a penalty range for refinancing too soon after purchase |
Ask each lender for these as line items, not a lump sum, and compare section A (lender charges) across quotes first. Services you are allowed to shop for are flagged on the Loan Estimate itself.
How to Complete the Process
- Read your current note and mortgage statement. Confirm your rate, remaining balance, whether you have an escrow account and whether a prepayment penalty applies (CBS News, undated). One evening's work, before you talk to any lender.
- Decide which refinance you are doing. Rate-and-term, cash-out, or a streamline (FHA streamline, VA IRRRL, USDA). Rate.com (Guaranteed Rate) publishes different application-to-closing estimates for each (Rate.com, undated), so this choice drives both your cost and your calendar. Mortgage insurance differs by program: a conventional refinance may require private mortgage insurance (PMI) depending on your equity, an FHA streamline keeps FHA mortgage insurance premiums (MIP), and a VA IRRRL carries a VA funding fee unless you are exempt.
- Gather documents. Recent pay stubs, two years of W-2s or tax returns if self-employed, bank and asset statements, homeowners insurance declarations, HOA statement if you have one, and your mortgage payoff information. Allow a few evenings; missing documents are the single most common cause of delay.
- Apply with two or three lenders in the same short window and collect Loan Estimates. Chase describes application-to-Loan-Estimate as the first defined step of the process (Chase, undated). Compare interest rate and APR side by side — the rate sets the payment, the APR reflects fees and points annualized.
- Choose a lender, lock your rate, and decide on points. Get the lock expiration date in writing; if the file runs past it, extensions cost money. Buying points to lower the rate is priced as a share of the loan amount (CBS News, undated).
- Let the appraisal happen, or confirm a waiver. The lender orders it; you give access. Houzeo publishes a refinance appraisal range for a single-family home (Houzeo, undated). Streamline programs may skip this (Rate.com, undated).
- Respond to underwriting conditions the day they arrive. Chase notes underwriting and loan preparation often takes the longest stretch of the process (Chase, undated). This is the only stage you can meaningfully speed up.
- Review the Closing Disclosure. For covered refinances, the lender must deliver it a minimum number of days before consummation (Lower, undated). Compare it line by line to your Loan Estimate and query anything that moved.
- Sign at closing. For a DC, Maryland or Virginia file, this is where the settlement company's all-inclusive refinance fee and lender's title premium appear (Federal Title & Escrow Company, undated).
- Wait out rescission, then confirm funding and payoff. Many refinances on a primary residence include a right-of-rescission waiting period before funds are disbursed (Lower, undated). FHA and VA loans being refinanced must be paid off in full within the window set by the program (AmeriSave, undated).
- Verify the old loan shows a zero balance, set up payment on the new one, and watch for your escrow refund. Chase notes most refinances close inside one typical window (Chase, undated); ask your loan officer for your file's dates in writing at step 5 and hold them to it.
Frequently asked questions
How much longer does a cash-out refinance take than a rate-and-term?
Rate.com (Guaranteed Rate) publishes separate application-to-closing estimates for rate-and-term and cash-out refinances, with cash-out running the longer of the two (Rate.com, undated) — more equity verification, more underwriting scrutiny, and an appraisal that actually has to support the cash you are taking. Rate.com also publishes a shorter window for prepared, qualified borrowers using an online mortgage lender (Rate.com, undated). Ask your lender for their own current estimate at application and get it in the file notes.
Is an FHA streamline or VA IRRRL cheaper and faster than a conventional refinance?
Faster, usually. Rate.com publishes a shorter application-to-closing estimate for streamline refinances than for rate-and-term or cash-out (Rate.com, undated), largely because income and appraisal requirements are reduced. Cheaper depends on the borrower: an FHA streamline keeps FHA mortgage insurance premiums (MIP) on the new loan, and a VA IRRRL adds a VA funding fee unless you are exempt, while a conventional refinance with enough equity can drop private mortgage insurance (PMI) entirely. Note also that FHA and VA loans being refinanced must be paid off in full after closing, or after six payments, within the window the program sets — whichever comes first (AmeriSave, undated).
I have a USDA loan. How long should I expect?
AmeriSave puts standard refinances on USDA loans in their own published timeframe, separate from conventional files (AmeriSave, undated), because the agency has to touch the file as well as the lender. Build the right-of-rescission waiting period on a primary residence (Lower, undated) into that total, and ask your lender in writing for the date they expect to fund.
What will the title and closing side cost in DC, Maryland or Virginia?
Federal Title & Escrow Company, which handles closings across DC, Maryland and Virginia, publishes an all-inclusive settlement fee for refinance closings and a minimum lender's title insurance premium for a refinance policy (Federal Title & Escrow Company, undated). Get their current figure for your loan amount directly, and ask any competing title company to quote the same two items so you are comparing like with like. In most states you can choose the settlement provider yourself, which is why these are worth shopping.
Can I be charged a penalty for refinancing a loan I only just took out?
Possibly. CBS News cites a prepayment penalty range for borrowers who refinance too soon after buying (CBS News, undated). Whether it applies to you is a question your current note answers in plain language — look for a prepayment rider. If one exists, add it to the total cost column before you compare a new Loan Estimate against your current payment, and ask a licensed professional to read the clause if the wording is unclear.
Sources
- Freddie Mac — Mortgage Rates Average 7.28% (2026-10-01)
- Rate.com (Guaranteed Rate) — How long does it take to refinance a house?
- Chase — How Long Does it Take to Refinance a Mortgage?
- Lower — How Long Does It Take to Refinance a Mortgage?
- AmeriSave — How Long Does It Take to Refinance a House in 2026? Timeline Breakdown
- CBS News (citing Freddie Mac) — Average mortgage refinance closing costs: What to know
- Mortgage.com — How Much Does It Cost to Refinance a Mortgage? (2026 Guide)
- Benzinga — What is the Average Cost to Refinance
- Houzeo — Appraisal Refinance: Meaning, Costs, and Types
- Federal Title & Escrow Company — Title Insurance Cost for Refinances
- Federal Title & Escrow Company — Title Insurance Costs for Refinances
Written by
Odalys Reyes Fontaine
Odalys explains zoning fights, property taxes, and the incentives that quietly steer where housing gets built. She treats real estate as a civic story as much as a financial one. She's partial to footnotes and long city council transcripts.