Big City vs. Suburb: How to Compare Housing Markets When Prices Don't Tell the Whole Story
National urban and suburban medians sit $75,000 apart, but the gap that decides your budget is the one inside your own metro — here is how to build it.
By Odalys Reyes Fontaine · Oct 06, 2026 · 10 min read
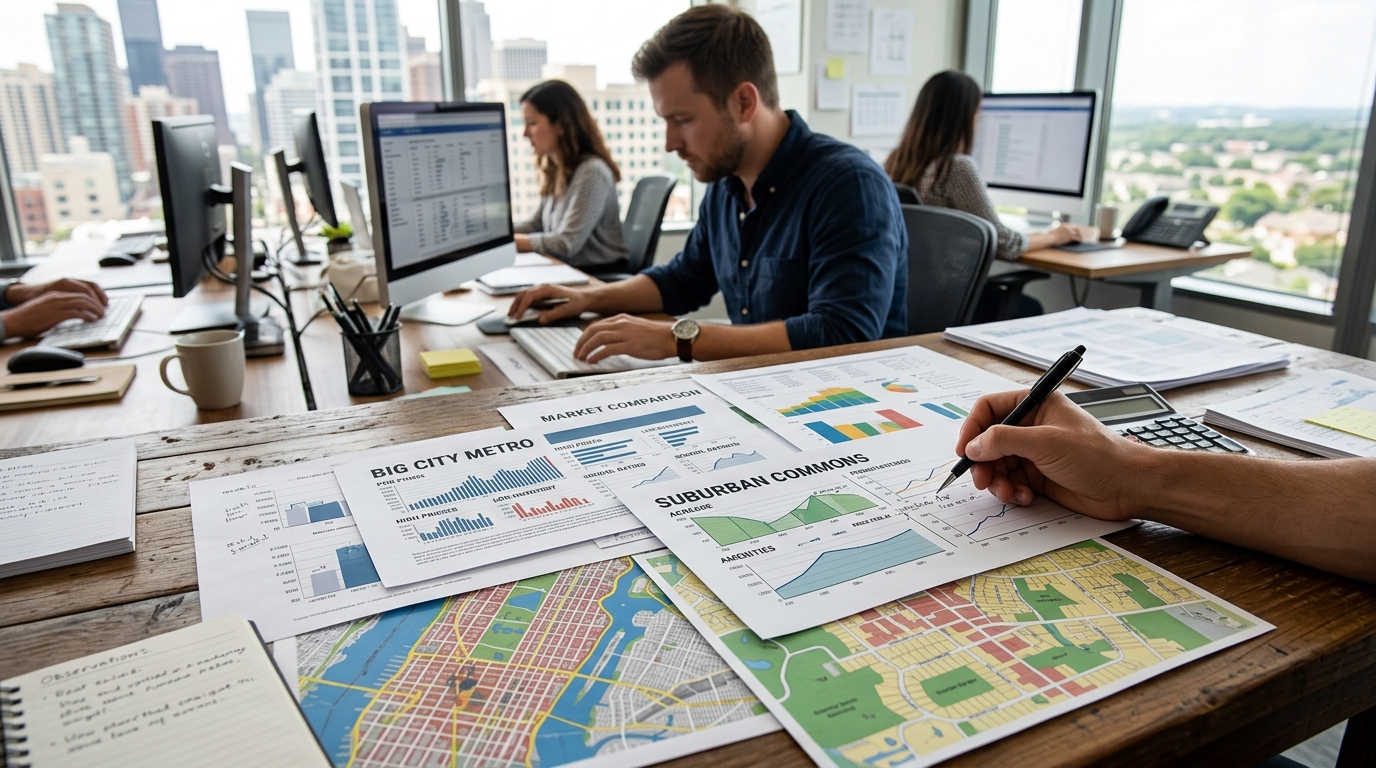
The headline price difference between a city neighborhood and a suburb usually hides three things: square footage, the property tax rate on each side of the municipal line, and what today's mortgage rate does to a larger loan. Redfin's national four-week read (reported by National Mortgage Professional, undated) put urban homes at $310,000 and suburban homes at $385,000 — a $75,000 gap — yet suburban price per square foot, $206, was only $1 above urban, at $205.
This guide builds the comparison from the same dated inputs on both sides, runs the monthly and five-year math at the mortgage rate Freddie Mac reported for Oct. 1, 2026, and shows where you have to substitute your own local numbers. These are national aggregates; they are not a read on your metro, your submarket, or any one address.
Side-by-Side Market Data
Both columns use the same source and the same measurement window, so the comparison is apples-to-apples: Redfin's four weeks ending Sept. 25, as reported by National Mortgage Professional (undated), paired with Freddie Mac's Primary Mortgage Market Survey for Oct. 1, 2026.
| Input | Urban (national) | Suburban (national) |
|---|---|---|
| Median sale price (Redfin, four weeks ending Sept. 25, via National Mortgage Professional, undated) | $310,000 | $385,000 |
| Year-over-year change, same report | +2.7% | +6.6% |
| Price per square foot, same report | $205 | $206 |
| Implied size (median price ÷ price per sq ft) | ~1,512 sq ft | ~1,869 sq ft |
| Property tax rate | Not reported in this dataset — look up your county/municipal effective rate | Not reported in this dataset — look up your county/municipal effective rate |
| Tax rate used in the math below (assumption, not a reported figure) | 1.00% of price | 1.00% of price |
| Homeowners insurance used below (assumption, not a reported figure) | $1,500/year | $1,500/year |
| Mortgage rate used (Freddie Mac PMMS 30-year fixed, Oct. 1, 2026) | 7.28% | 7.28% |
| Loan amount at 20% down, 30-year term | $248,000 | $308,000 |
| Principal and interest | $1,697/mo | $2,107/mo |
| Taxes and insurance at the assumptions above | $383/mo | $446/mo |
| Total monthly payment | $2,080 | $2,553 |
Four things to hold onto before you reuse this table.
- The $1 per-square-foot difference is the story, not the $75,000 price gap. Redfin says urban homes are the least expensive because they are typically the smallest (via National Mortgage Professional, undated). Suburban price per square foot exceeding urban was a first since Redfin began tracking the series in 2018.
- The property tax rate row is blank on purpose. It is not in this dataset, and it is often the single largest line item that changes when you cross a city line — municipal, county, and school district levies stack differently. Get the effective rate from the assessor on each side and replace the 1.00% placeholder.
- The Freddie Mac rate is a weekly national average collected from thousands of loan applications submitted through Loan Product Advisor, released Thursdays at noon ET and covering the prior Thursday through Wednesday (Freddie Mac, Oct. 1, 2026). It is not a quote. Your rate depends on credit, down payment, loan type (conventional, FHA, VA, jumbo), and lender.
- The same Redfin report put rural median sale price at $333,000, up 4% — useful if your third option is further out.
Condo and HOA costs are not in any of these figures. If one side of your comparison is a condo or a covenanted subdivision, add the monthly HOA dues and any special assessment history as a separate line.
Cost of Living and Affordability Comparison
Here is the arithmetic, using only the inputs in the table above. Replace the tax and insurance assumptions with your local figures and rerun it.
Step 1: monthly payment, 30-year fixed at 7.28% (Freddie Mac, Oct. 1, 2026), 20% down
- Urban: $310,000 price − $62,000 down = $248,000 loan. At 7.28% over 360 months, principal and interest is $1,697.
- Taxes at the 1.00% placeholder: $3,100/year ÷ 12 = $258. Insurance at $1,500/year ÷ 12 = $125.
- Urban total: $1,697 + $258 + $125 = $2,080/month.
- Suburban: $385,000 price − $77,000 down = $308,000 loan. At the same rate and term, principal and interest is $2,107.
- Taxes: $3,850/year ÷ 12 = $321. Insurance: $125.
- Suburban total: $2,107 + $321 + $125 = $2,553/month.
- Gap: $473/month, or $5,676/year, plus $15,000 more cash at closing for the larger down payment.
Step 2: what the $473 buys
The implied size difference is 1,869 − 1,512 = 357 square feet. $473 ÷ 357 = $1.32 per extra square foot per month. Whether that is a good trade depends on whether you need the space; it is not a statement about which market performs better.
Step 3: five-year total cost
| Line | Urban | Suburban |
|---|---|---|
| Down payment | $62,000 | $77,000 |
| 60 monthly payments | $124,800 | $153,180 |
| Total cash out | $186,800 | $230,180 |
| Less principal paid in 60 months | −$13,872 | −$17,228 |
| Net five-year cost | $172,928 | $212,952 |
Difference over five years: $40,024. Note that $3,356 of the suburban spending comes back as equity, which is why the net gap is smaller than the $43,380 difference in cash out.
Step 4: the break-even on transaction costs
Assume 8% round-trip costs — agent commissions, transfer taxes, title, and closing fees vary widely by state and by negotiation, so treat 8% as a placeholder you confirm locally. That is $24,800 on the urban purchase and $30,800 on the suburban one.
- At 36 months, principal paid is about $7,714 urban and $9,580 suburban — roughly $17,000 and $21,000 short of covering those costs.
- Principal paid reaches the assumed round-trip cost at about month 95 — just under eight years — on both sides, because the rate and the cost percentage are identical. The timeline is the same; the dollars at risk are not. Nothing here assumes any price change in either direction, and no one can tell you what prices will do.
Step 5: two variations worth running
- A 15-year fixed averaged 6.60% on Oct. 1, 2026 (Freddie Mac). On the same loan amounts, principal and interest becomes about $2,174 urban and $2,700 suburban — higher monthly, far more principal built early.
- A year earlier the 30-year averaged 6.34% (Freddie Mac). Rolling prices back by the reported year-over-year changes (urban $301,849, suburban $361,163) and applying 6.34%, principal and interest would have been about $1,501 urban and $1,796 suburban. Combined price and rate movement added roughly $196 and $311 a month respectively.
Bottom Line: Which Option Fits Your Situation
The data above does not pick a winner in the abstract. It picks one once you name your time horizon and your cash position.
You expect to move within three years. At 36 months you have built about $7,714 in principal on the urban purchase and $9,580 on the suburban one, against assumed round-trip costs of $24,800 and $30,800. Neither side clears the break-even at roughly month 95. In that window the numbers favor the lower-price, lower-friction option — the $310,000 urban purchase costs $473 a month less and ties up $15,000 less cash at closing — or renting while you wait, if the rent in your target neighborhood is below $2,080 for comparable space. This is the one scenario where the extra 357 square feet is hardest to justify.
You expect to stay seven years or more and need the space. The roughly 95-month break-even sits inside your horizon, and the suburban premium works out to $1.32 per extra square foot per month. If a growing household would otherwise rent storage, add a room, or move again inside five years, paying $473 more for 357 square feet is a straightforward trade. The thing to verify first is the tax rate, because the 1.00% placeholder is doing a lot of work: a one-point difference in effective rate on $385,000 is $3,850 a year, which would swamp most of the per-square-foot logic.
You have strong income but limited cash. The binding constraint is the $15,000 difference in down payment, not the $473 monthly gap. Lower-down-payment loan types — FHA, VA for eligible borrowers, or conventional programs under 20% — change both the loan amount and the monthly cost through mortgage insurance, and they are not reflected anywhere in the math above. Rerun Step 1 with the actual down payment and mortgage insurance your lender quotes before deciding the suburb is out of reach.
You are deciding whether to act now at all. The only current data points here are national: urban median $310,000, up 2.7%; suburban $385,000, up 6.6% (Redfin via National Mortgage Professional, undated); and a 30-year average of 7.28%, up from 7.03% the prior week and 6.34% a year earlier (Freddie Mac, Oct. 1, 2026). None of that tells you what is happening in your metro, your school district, or on your street — and suburban price growth outpacing urban nationally is not evidence that it is doing so where you are buying. Pull the same four figures for your two specific submarkets, from one source, for one dated period, and run Steps 1 through 4 again.
For anything transaction-specific — disclosure duties, assessment caps, transfer taxes, HOA documents, condo warrantability — get a licensed agent, a real estate attorney where your state uses one, and a tax professional to look at the actual property.
Frequently asked questions
Why is suburban price per square foot higher than urban?
Redfin's four-week read put suburban at $206 and urban at $205 per square foot — the first time suburban exceeded urban since the series began in 2018 (via National Mortgage Professional, undated). The $75,000 difference in median price ($385,000 vs. $310,000) is mostly size, not quality: Redfin attributes lower urban prices to urban homes typically being the smallest. That works out to roughly 1,512 versus 1,869 square feet at those medians.
Does the $75,000 national gap apply to my metro?
No. The $310,000 and $385,000 medians are national aggregates for the four weeks ending Sept. 25 (Redfin via National Mortgage Professional, undated). In some metros the city median sits above the suburban one; in others the gap is far wider than $75,000. Pull both figures for your two specific submarkets from a single source and a single dated period before reusing any of the math here.
How much did the rate change cost me compared with last year?
On the suburban side, the same report's year-over-year figures imply a $361,163 price a year ago at the then-average 6.34% (Freddie Mac), giving about $1,796 in principal and interest with 20% down. At $385,000 and 7.28% (Freddie Mac, Oct. 1, 2026), it is $2,107 — about $311 more a month from price and rate combined. The 30-year also rose from 7.03% the prior week.
Would a 15-year loan change the city-versus-suburb decision?
It changes the monthly gap more than the choice. At 6.60% (Freddie Mac, Oct. 1, 2026), principal and interest on the $248,000 urban loan is about $2,174 and on the $308,000 suburban loan about $2,700 — a $526 difference, versus $410 in principal and interest at 7.28% over 30 years. It also builds principal far faster, which pulls the roughly 95-month break-even on assumed 8% round-trip costs forward.
Suburban prices rose 6.6% — should I hurry?
That 6.6% is a national year-over-year figure for one four-week window (Redfin via National Mortgage Professional, undated), not a forecast and not a reading on your market. A past increase from roughly $361,000 to $385,000 nationally says nothing about what any specific suburb will do next. The figures that should drive your timing are your own submarket's price trend, inventory, and the actual rate a lender quotes you.
Sources
- National Mortgage Professional (citing Redfin) — Redfin: Square Footage Now Worth More In Suburbs
- Freddie Mac — Mortgage Rates - Primary Mortgage Market Survey (PMMS) (2026-10-01)
Written by
Odalys Reyes Fontaine
Odalys explains zoning fights, property taxes, and the incentives that quietly steer where housing gets built. She treats real estate as a civic story as much as a financial one. She's partial to footnotes and long city council transcripts.