Should You Rent or Buy in Tampa? Here's the Math
Tampa's average rent sits near $1,995 a month, and a 20%-down loan at the 6.22% national 30-year average lands close to it — the rest is upkeep and time.
By Desmond Achebe-Park · Oct 06, 2026 · 7 min read
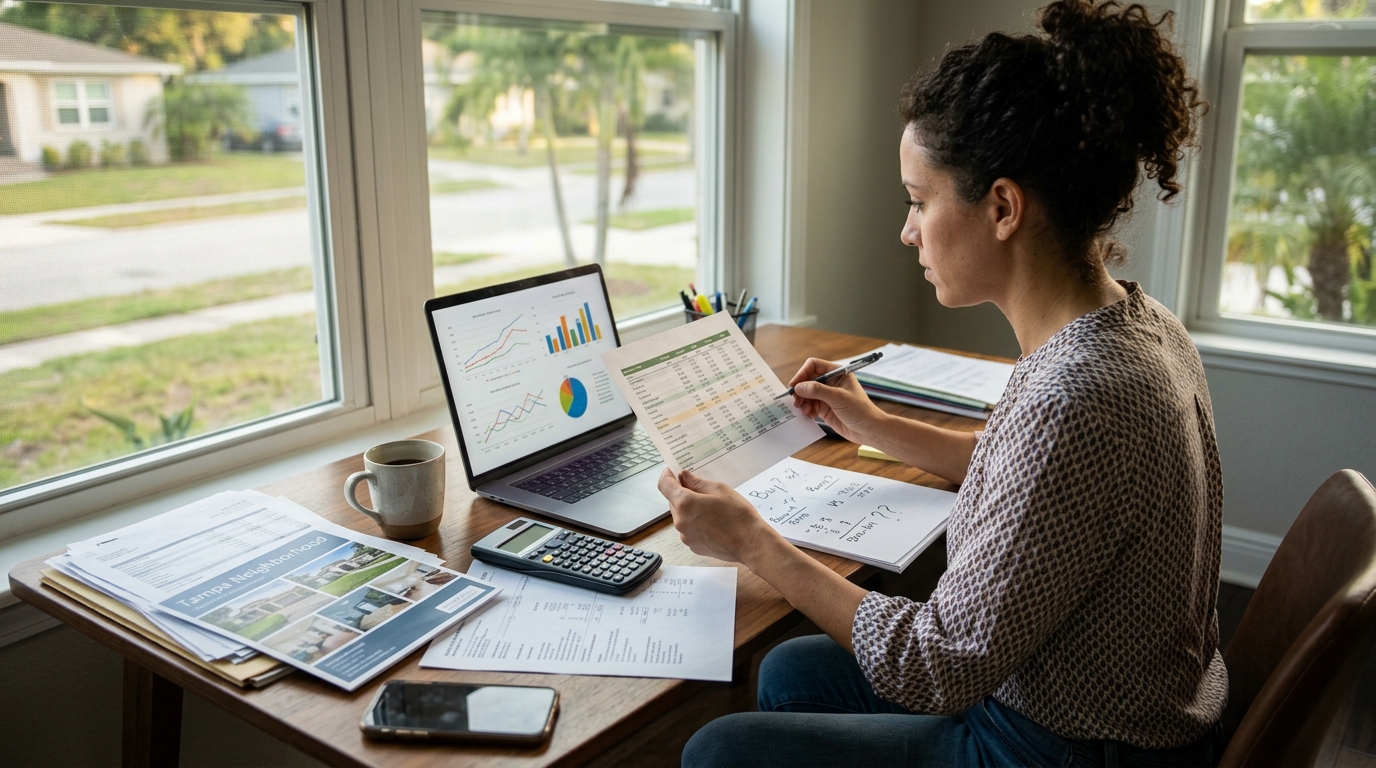
Renting and buying in Tampa are closer on the monthly number than most people expect. The average Tampa rent across all bedrooms and property types is $1,995 a month (Zillow, 2026-10-04), while principal, interest and property tax on a $283,000 purchase with 20% down work out near $1,682 a month before you add a homeowners insurance quote. The decision turns on insurance, repairs, upfront cash and how many years you plan to stay.
The table below uses one price and one down payment throughout so you can swap in your own figures. It is a worked example, not a quote, and your rate, taxes and insurance will come from your own lender and insurer.
The Rent vs. Buy Math
Every buying figure below uses the same purchase price and down payment, stated in the final row. Insurance is left blank on purpose: Florida windstorm and flood pricing varies too much by address, roof age and elevation for a single number to be useful, and no sourced figure exists for this guide.
| Line item | Rent in Tampa | Buy in Tampa |
|---|---|---|
| Monthly housing payment | $1,995 average rent, all bedrooms and all property types (Zillow, 2026-10-04) | About $1,390 in principal and interest on a $226,400 30-year fixed loan at the 6.22% national average rate (Freddie Mac, 2026-03-19) |
| Property tax | Built into the rent | About $292 a month, applying Tampa's 1.24% median effective property tax rate to a $283,000 price (Ownwell, 2026-04-13) |
| Homeowners insurance | Renters policy only, your quote | Your quote — get a bound Florida quote for the exact address before you commit |
| Repairs, HOA or condo dues | Landlord's cost under the lease terms | Yours, plus any Hillsborough County condo or HOA dues and special assessments |
| Cash at the start | First month, plus deposit or last month as your Tampa lease sets | $56,600 down (20%) plus closing costs from your lender's Loan Estimate |
| Principal paid after 12 months | $0 | About $2,625 |
| Principal paid after 5 years | $0 | About $15,170 |
| Monthly running total | $1,995 | About $1,682 before insurance, maintenance and any HOA |
| Assumptions | $283,000 purchase price — the median sale price in North Tampa last month, up 4.6% year over year (Redfin) — with 20% down ($56,600), a $226,400 30-year fixed loan at 6.22% (Freddie Mac, 2026-03-19) and Tampa's 1.24% median effective tax rate (Ownwell, 2026-04-13). Freddie Mac's survey rate assumes a conventional, conforming, fully amortizing purchase loan with 20% down and excellent credit, so FHA, VA and jumbo pricing will differ. |
Swap the price and the gap moves fast. Northwest Tampa's median sale price was $411,000 last month, down 2.0% year over year (Redfin) — the same 20% down there means $82,200 in cash and a payment roughly 45% higher than the North Tampa example.
When Renting Wins
- You expect to leave Tampa inside three years. Five years of payments on the $226,400 example loan build about $15,170 of principal, and the first 12 months build only about $2,625. Sell before the equity covers your selling costs and you are paying for the privilege of having owned.
- The $56,600 down payment would leave you under six months of reserves. At $1,995 a month, the Tampa average rent, six months of housing is $11,970. If writing the down payment check plus closing costs drops you below that, renting keeps the cushion.
- Your Florida insurance quote, repairs budget and HOA dues come to more than $313 a month. That is the gap between $1,995 average Tampa rent and the $1,682 principal, interest and tax floor. Above it, owning that $283,000 home costs more every month, not less.
- Your income is variable or your job is new. A $1,995 monthly rent you can leave at the end of a lease term is easier to unwind than a 30-year loan at 6.22%, and lenders price self-employed and thin-credit files differently from the 20%-down, excellent-credit borrower the Freddie Mac average reflects.
- Tampa rents have not only moved one way. The average was $2,213 in April 2025 (Zillow, reported by FOX 13 News) and $1,995 in October 2026 (Zillow) — renewal pricing is negotiable in some Tampa buildings, and worth testing before you assume buying is the only way to control the number.
When Buying Wins
- You plan to stay five years or longer. That is when the example loan has paid down roughly $15,170 of principal rather than the $2,625 of the first year, which gives selling costs something to come out of.
- You already pay more than $1,995 a month in Tampa rent. Against the $1,682 monthly floor on a $283,000 purchase, the gap gives you room to absorb an insurance premium and a repair fund and still break even on cash flow.
- You are shopping nearer $283,000 than $411,000. The North Tampa median keeps the down payment at $56,600 instead of the $82,200 that Northwest Tampa's $411,000 median requires at 20% down (Redfin).
- You can carry the 15-year payment. The 15-year fixed averaged 5.54% against 6.22% on the 30-year (Freddie Mac, 2026-03-19). The monthly payment is higher, but the principal position at year five is far ahead of the $15,170 in the table.
- You want a fixed base payment and can absorb a tax bill of $3,477 a year. That is Tampa's median annual property tax bill, $1,077 above the $2,400 national median (Ownwell, 2026-04-13), and it is a cost renting hides from you.
Run Your Own Numbers
- Write down your current Tampa rent. Use the real number on your lease, not the $1,995 Tampa average (Zillow, 2026-10-04), and add your renters insurance premium and any parking or pet fees your building charges.
- Set a target price and down payment. Multiply the price by your down payment percentage — 20% of $283,000 is $56,600 — and subtract to get the loan amount. If you are putting less than 20% down, ask your lender what mortgage insurance adds each month.
- Get a real rate quote for your loan type. Compare it to the 6.22% 30-year and 5.54% 15-year averages (Freddie Mac, 2026-03-19), remembering those assume a conventional conforming loan with 20% down and excellent credit. FHA, VA and jumbo quotes will not match.
- Add the tax line. Multiply your target price by Tampa's 1.24% median effective property tax rate (Ownwell, 2026-04-13) and divide by 12. On $283,000 that is about $292 a month. Hillsborough County's actual assessment and any homestead treatment will change it — confirm with the property appraiser's office.
- Get a bound homeowners insurance quote and the HOA figure for the exact address. Add a monthly repair allowance you choose. Only now compare the total to step 1.
- Divide your upfront cash by the monthly gap, then test it against your timeline. If the down payment and closing costs take 60 months of savings to recover and you expect to leave Tampa in 24, the table above is telling you to keep renting. Before you sign either a lease or a contract, run the specific numbers past a Florida-licensed agent, a lender and a tax professional.
Frequently asked questions
How much of my payment actually builds equity in year one?
On a $226,400 Tampa loan at 6.22% (Freddie Mac, 2026-03-19), about $2,625 of principal in the first 12 months — roughly $219 a month out of a $1,390 principal-and-interest payment. The rest is interest. Equity from price changes is separate and not something anyone can promise you.
Is buying cheaper than renting in Tampa right now?
On the monthly floor, yes: about $1,682 in principal, interest and tax on a $283,000 purchase with 20% down versus $1,995 average Tampa rent (Zillow, 2026-10-04). That $313 gap has to cover your Florida homeowners insurance, repairs and any HOA dues before the comparison holds.
What if I can only put 5% or 10% down?
Your loan grows — 10% down on $283,000 means a $254,700 loan instead of $226,400 — and the 6.22% Freddie Mac average will not apply, since that survey assumes 20% down and excellent credit. Ask your lender for a quote with mortgage insurance included before comparing to $1,995 rent.
Does the neighborhood I pick change the math much?
Substantially. North Tampa's median sale price was $283,000 last month and Northwest Tampa's was $411,000, down 2.0% year over year (Redfin). At 20% down, that is $56,600 versus $82,200 in cash, and the tax bill at Tampa's 1.24% effective rate scales with price.
Sources
- Zillow — Average Rental Price in Tampa, FL | $1,995 (2026-10-04)
- Zillow (reported by FOX 13 News) — Tampa average rent prices higher than national average: Zillow report (2025-04-30)
- Freddie Mac — Average 30-Year Fixed-Rate Mortgage at 6.22% (2026-03-19)
- Ownwell — Tampa, Hillsborough County, Florida Property Taxes - Ownwell (2026-04-13)
- Redfin — North Tampa, Tampa Housing Market: House Prices & Trends
- Redfin — Northwest Tampa, Tampa Housing Market: House Prices & Trends
Written by
Desmond Achebe-Park
Desmond covers the renter's side of the market, from lease fine print to the etiquette of negotiating with landlords. He's interested in how small cities absorb people priced out of bigger ones. He writes with a skeptic's eye toward anything called a 'luxury amenity.'