How to Sell an Inherited House: Step-by-Step Guide
From probate paperwork and date-of-death valuations to clearing the house, pricing it, and getting every heir to sign at closing without stalling the deal.
By Tobias Lindqvist · Oct 06, 2026 · 16 min read
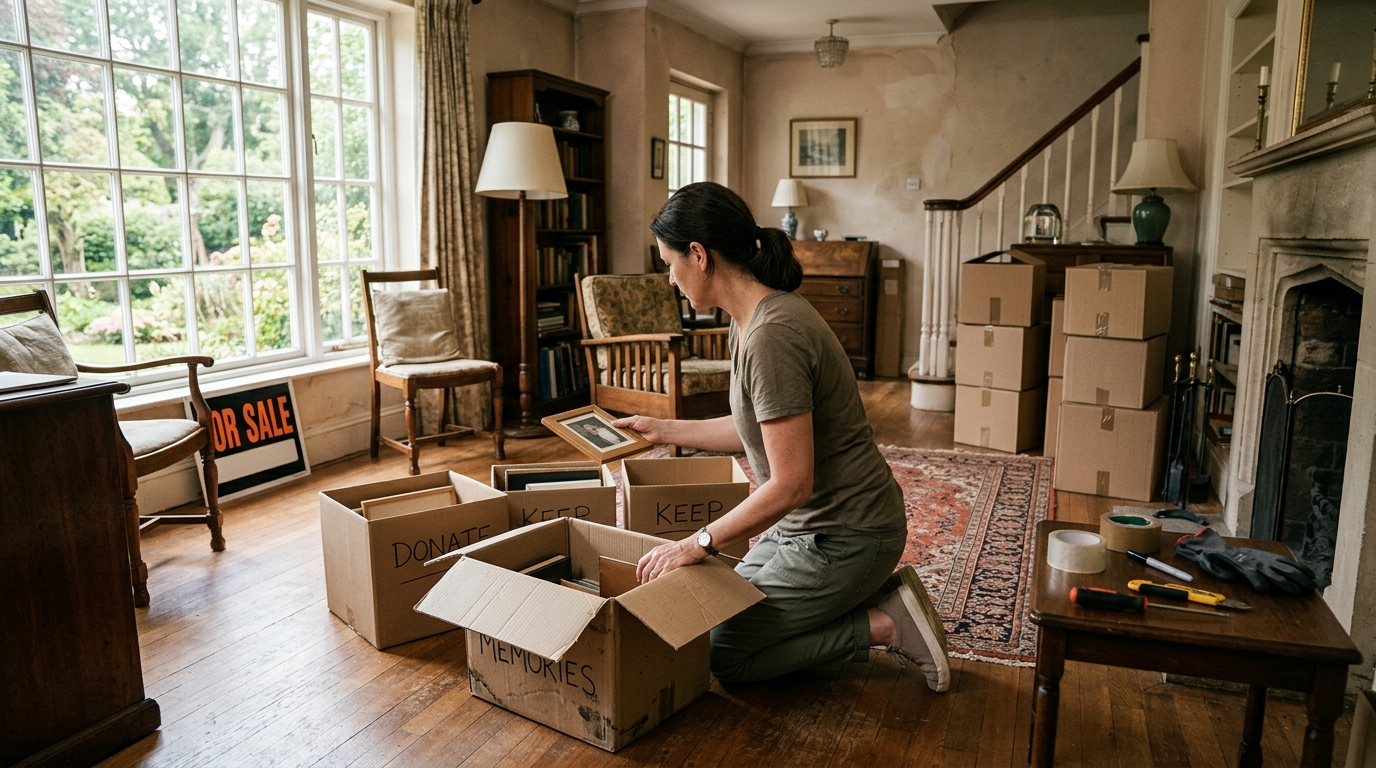
Selling a house you inherited is two jobs stacked on top of each other: settling an estate and running a normal home sale. The estate part — proving you have legal authority to sell, establishing the tax basis, and getting co-heirs to agree — usually controls the calendar. The sale part only starts moving once title can actually transfer.
This guide walks the sequence in order, flags where costs land, and names the sources to pull current figures from. Probate rules, transfer taxes, and disclosure duties are set state by state, so treat anything here as a checklist to take to a probate attorney, a tax professional, and a local agent — not a substitute for their advice on your specific estate.
Selling Timeline Overview
Think in four phases. The first one is the wild card, and it is the reason inherited-home timelines are so much wider than ordinary ones.
Phase 1 — Authority to sell (the probate phase). Nothing else can finish until someone has the legal power to sign a deed. Probate timelines for selling an inherited house vary widely by complexity (Opendoor, undated), and the spread between states is real:
- California publishes its own probate timeline, plus a small-estate affidavit route with a dollar threshold (Opendoor, citing California Courts, undated).
- Texas offers independent administration, which carries a shorter published timeline than supervised administration (Opendoor, citing the Texas State Law Library, undated).
- Florida publishes a formal probate timeline and a separate summary administration track with its own threshold (Opendoor, citing the Florida Bar, undated).
- Ohio sets a filing deadline for the estate inventory and a defined creditor claim period (SearchColumbusHomesOnline, undated), and title companies often wait on those dates.
Opendoor, citing Nolo (undated), gives a typical overall range from date of death to completed closing. Look up the current figure and treat it as the outer envelope, not a promise — a contested will, a missing heir, or an unfiled inventory can push past any published range.
Phase 2 — Prep and pricing. This phase is yours to compress or stretch. It covers clearing contents, a pre-listing inspection, any repairs you choose, photography, and a decision on staging. If the house is full of fifty years of belongings, clearing it is usually the long pole, not the repairs.
Phase 3 — On market to under contract. For the national benchmark, use the median time on market for existing-home sales that the National Association of Realtors publishes with its monthly Existing-Home Sales release (NAR, August 2025). That is a national median across all housing types for one month — your metro, your price band, and your property type (single-family, condo, multifamily) can each sit well above or below it. Ask your agent for the median days on market for comparable sales in your submarket over the last 90 days, and plan around that number instead.
Seasonality matters too, but only as a local statistic: ask for monthly days-on-market and active-inventory counts for your ZIP code over the past three years. In some markets winter listings sit longer; in others, low winter inventory shortens them. Don't apply a national seasonal rule to a local street.
Phase 4 — Under contract to closing. This runs on the buyer's loan type. Conventional, FHA, VA, and jumbo files move at different speeds and have different appraisal and condition requirements; FHA and VA appraisals can flag repair items a conventional appraisal would not. Cash closings skip the loan timeline but still wait on title, and an estate sale adds a title step: the title company has to confirm your authority, the creditor period, and that every heir on title has signed.
A practical way to sequence it: start Phase 2 while Phase 1 is still running. Clearing the house, getting the inspection, and interviewing agents do not require letters testamentary. Signing a listing agreement and accepting an offer usually do — confirm with the estate's attorney which steps your state lets you take before authority is granted.
Step-by-Step Process
- Pull the deed and find out how title is held. Order a copy from the county recorder's office (counties charge a small per-page or per-copy fee, set locally — ask the recorder for the current rate). How the property is titled determines whether it passes by survivorship, by trust, or through probate, and that determines everything after it.
- Open the estate, or confirm you don't have to. File the will and petition the probate court in the county where the decedent lived, or use your state's simplified route if the estate qualifies. Court filing fees are set by state statute and county — ask the clerk's office for the current schedule before you file. If an attorney handles it, get the fee basis in writing: flat fee, hourly, or a statutory percentage of the estate, depending on your state.
- Order a retrospective appraisal as of the date of death. This is the number your tax basis rests on, because the IRS resets an inherited property's cost basis to fair market value on the date of the original owner's death (SmartAsset, undated). Hire a licensed appraiser and specify a retrospective date-of-death valuation; quotes run above a standard purchase appraisal because of the research involved, so get two or three written quotes. Do not substitute an online automated estimate — a Zestimate or any AVM is a computer model, not a market or appraised value, and the IRS will not treat it as one.
- Secure and insure the vacant house. Call the decedent's insurer the week you take responsibility. Most standard homeowners policies restrict coverage once a house is unoccupied for a set number of days, and you may need a vacant-property endorsement or policy, which typically prices higher than standard coverage. Ask your carrier for a written quote and the exact vacancy threshold in days. Change the locks, keep utilities on for inspections and showings, and keep the lawn cut.
- Clear the contents and put the heir agreement in writing. Divide personal property before you list, not during escrow. Get written sign-off from every heir on: who takes what, the minimum acceptable price, who pays carrying costs in the meantime, and how proceeds split. Estate-clearing and junk-removal companies price by truckload volume or by the room — collect at least two itemized written quotes, and ask whether resale of contents offsets any of the fee.
- Order a pre-listing inspection. HomeAdvisor's figures (via Rocket Mortgage, 2026) give a national average and typical price range for a home inspection, and NAR published its own 2025 average (House Beautiful, republished by NAR, 2025); cost varies with home size (Rocket Mortgage, October 2025), so a large house will quote above the average and a small condo below it. Use the report to decide what you'll repair, what you'll disclose, and what you'll price for. On an older inherited house this is usually the single most useful few hundred dollars you'll spend, because it stops surprises from blowing up a contract later.
- Get three net-proceeds sheets, not three fee quotes. Ask a listing agent, a cash-offer buyer (national iBuyer platforms and local investors both bid this way), and — if you're considering it — a flat-fee or FSBO service to each put a written estimate in front of you showing gross price minus every deduction: commission, concessions, repair credits, carrying costs during the marketing period, and closing fees. A lower fee attached to a lower offer can net you less than a full-commission listing. Compare the bottom line only. The right answer depends on your situation: heirs who need speed and certainty weigh differently than heirs who can carry the house for a few months.
- Set the list price yourself, from two inputs. Take the agent's comparative market analysis on closed sales in the last 90 days within your submarket and property type, and read it next to the date-of-death appraisal. The NAR median existing-home price for all housing types (NAR, August 2025) is a national reference point only — it tells you nothing about your block. Decide your list price and your walk-away floor before the first showing, and have every heir initial both.
- Decide on prep and staging as a budget line. Professional staging has a published national cost range and average (HomeAdvisor, via Bankrate, 2025), and an initial stager consultation is priced separately and far lower (HomeAdvisor, via Bankrate, 2025). NAR's 2025 Profile of Home Staging reports the share of seller's agents who said staging increased the sale price (via Homes.com, 2025) — worth reading before you decide, and especially relevant for an empty inherited house where buyers struggle to judge room scale. No renovation or staging spend is guaranteed to come back at resale; treat it as a marketing decision with a known cost and an unknown return.
- Complete disclosures and plan the signing. Fill out your state's seller disclosure form personally, disclosing what you actually know. Many states give estate and fiduciary sellers a partial exemption because you never lived in the house — confirm whether yours does and what it still requires, because an exemption from the form is not an exemption from disclosing known material defects. Then ask the title company, well before closing, exactly who must sign and whether out-of-state heirs need a notarized power of attorney or remote online notarization, and get those documents prepared early.
Costs to Budget For
Ask for each of these as a written range from the provider in your market. Rates, taxes, and who-pays-what customs vary by state, county, and even by negotiated contract — a figure from another metro will mislead you.
| Cost | Basis and how to price it |
|---|---|
| Real estate commission | A percentage of sale price. Clever Real Estate publishes a national average commission rate (undated), split between the listing agent and the buyer's agent, and converts it to a dollar amount at the median U.S. home price (undated). It is negotiable, varies by market and price band, and the buyer-side portion is now a separate negotiation in many transactions — get your rate in the listing agreement in writing. |
| Seller-paid buyer concessions | A percentage of price or a flat credit, negotiated per deal. More common when inventory is high in your submarket; ask your agent what share of recent comparable closings included a concession. |
| Title, escrow and settlement fees | Charged per transaction, often on a published rate schedule filed with the state insurance department. Call a local title company for a written quote before you list. |
| Transfer, deed or documentary stamp tax | Set by state and sometimes city or county, usually as a rate per $500 or $1,000 of price, or a flat percentage. Some states charge the buyer, some the seller, some split it. Confirm the rate and the customary payer with the county recorder. |
| Owner's title policy (where seller pays) | Premium based on sale price, on a filed rate schedule; customary payer varies by state and county. |
| Date-of-death appraisal | Flat fee per report, quoted higher than a standard purchase appraisal because of the retrospective research. Get two or three quotes. |
| Pre-listing home inspection | HomeAdvisor's national average and range (via Rocket Mortgage, 2026) and NAR's 2025 average (via House Beautiful/NAR, 2025) are the benchmarks; price scales with home size (Rocket Mortgage, October 2025). |
| Staging | HomeAdvisor's published national range and average for professional staging (via Bankrate, 2025); a consultation only is priced in a much lower range (via Bankrate, 2025). Vacant-home staging costs more than occupied staging and is usually billed monthly. |
| Clear-out and junk removal | Priced by truckload volume or per room. Two itemized quotes minimum. |
| Repairs and deferred maintenance | Quoted per item. On an inherited house, roof, HVAC, sewer line, and electrical panel are the big-ticket unknowns — price them from the inspection report, not a guess. |
| Probate court filing and attorney fees | Court fees set by statute and county; attorney fees charged flat, hourly, or as a statutory percentage of the estate depending on the state. |
| Carrying costs while the estate settles | Monthly: property taxes, vacant-home insurance premium, utilities, lawn and snow service, HOA dues if it's a condo or in an association. Multiply your monthly figure by a realistic probate timeline — this is the cost most heirs underestimate. |
| Capital gains tax on post-death appreciation | Only on appreciation after the date-of-death basis (SmartAsset, undated). Rate depends on your income and filing status; ask a tax professional before you sign a contract, not after. |
Do not add these into one number from a template. Build your own net sheet with your market's actual quotes, and keep a contingency line for repair credits negotiated after inspection.
Common Mistakes That Delay or Derail a Sale
- Signing a listing agreement before you have legal authority to sell. You end up under contract with a buyer you cannot convey to. The buyer walks or renegotiates, and you restart marketing from zero — adding another full cycle of your market's median days on market (the national benchmark is NAR's monthly median time on market for existing-home sales, August 2025) on top of the probate wait you were trying to skip.
- Skipping the date-of-death appraisal. Without it you have no defensible basis, and the IRS computes gain only on appreciation after inheritance (SmartAsset, undated) — which you cannot prove. The consequence is a tax bill on gain you may not have, plus an appraiser trying to reconstruct a value years later at a higher fee.
- Letting the insurance lapse or run on an occupied-home policy. Carriers restrict coverage after a set vacancy period. A burst pipe in an uncovered vacant house turns into a repair bill you pay out of estate funds, a cancelled contract, and months of remediation before you can relist.
- Listing before the heirs agree in writing on price and split. One heir refusing to sign at the closing table kills the deal at the last step, after the buyer has paid for an appraisal and inspection. You lose the buyer, the deposit dispute starts, and the house goes back on market carrying the stigma of a failed contract.
- Pricing off an online estimate. A Zestimate or any automated valuation is a model output, not a market or appraised value. Overpricing against a local CMA means a listing that sits past the comparable median days on market and then takes a price cut — and buyers can see both the price history and the accumulated days on market.
- Selling as-is without an inspection you've read. The buyer's inspector finds the sewer line or the panel instead of yours, mid-contract, with leverage. You either credit the repair at the buyer's quoted price or lose the contract and relist, restarting the clock.
- Choosing the offer with the lowest fee instead of the highest net. A cash offer that closes quickly can net less than a listed sale after the discount to market, and a listed sale can net less than a cash offer once you add several months of carrying costs. Without written net sheets, you find out at closing, when you can no longer change it.
- Ignoring the condo or HOA layer. Associations control document delivery, estoppel or resale certificate fees, and sometimes transfer approvals. Ordering those documents in the last week of escrow delays closing until the association produces them on its own schedule.
Frequently asked questions
Can we skip probate entirely?
Sometimes, if the estate is small enough or the property passed by trust or survivorship. Several states publish dollar thresholds for a simplified route: California has a small-estate affidavit threshold (Opendoor, citing California Courts, undated), Florida has a summary administration threshold (Opendoor, citing the Florida Bar, undated), and Ohio has a Summary Release from Administration for smaller estates (SearchColumbusHomesOnline, undated). Call the probate clerk in the county where the decedent lived and ask for the current threshold figure and form — the numbers change by statute, and real property sometimes counts differently than cash.
How long do creditors have to make a claim, and does that hold up closing?
It can. Ohio, for example, sets both a deadline for filing the estate inventory and a defined creditor claim period (SearchColumbusHomesOnline, undated), and title companies frequently want that window closed — or an indemnity in place — before they will insure the sale. Texas's independent administration route carries a shorter published timeline than supervised administration (Opendoor, citing the Texas State Law Library, undated). Ask your title company in week one what it requires; that answer, not the court's, usually sets your earliest realistic closing.
What if the house was owned jointly with a surviving spouse?
The step-up is not automatic on the whole property. Jointly owned property inherited from a decedent receives a step-up in basis only for the portion the decedent owned, unless it is a community-property asset (Geiger Law Office, undated). That exception matters a great deal in community-property states, where the full value can step up. Get a tax professional to confirm which applies before you set a sale date, because it changes the gain on an identical sale price.
Should one of the heirs move in instead of selling?
It's a real option with a specific threshold. If an heir moves into an inherited home as a primary residence and lives there at least two of the five years before sale, the Section 121 exclusion can shelter capital gain from tax (Thrivent, undated). That means a two-year commitment, plus buying out the other heirs and carrying the property in the meantime. Run it past a tax professional alongside the stepped-up basis you already have, since the step-up may already reduce the gain enough that waiting two years isn't worth it.
Is staging worth paying for on an empty house?
It depends on how buyers in your price band shop and what the empty rooms look like. NAR's 2025 Profile of Home Staging reports the share of seller's agents who said staging increased the sale price (via Homes.com, 2025) — read the actual figure before deciding. If the full staging range (HomeAdvisor, via Bankrate, 2025) is more than the estate wants to spend, a stager's initial consultation is priced in a far lower range (HomeAdvisor, via Bankrate, 2025) and buys you a written list of what to fix, paint, or remove that you can execute yourself. No staging spend is guaranteed to come back in the sale price.
How do we compare a cash offer against listing with an agent?
On net proceeds and on time, never on the commission rate alone. Build both columns: gross offer, minus commission (Clever Real Estate publishes a national average rate and its dollar equivalent at the median U.S. home price, undated), minus concessions, repairs, title and transfer costs, minus carrying costs for each month the listed route would take. Then weigh the certainty difference — a cash buyer removes appraisal and financing risk, which has real value when several heirs are splitting proceeds and one of them needs the money now. Get at least two cash bids and one agent listing estimate so you're comparing a market, not a single number.
Sources
- SmartAsset — Capital Gains Tax on Inherited Property
- Thrivent — How Does the Capital Gains Tax on Inherited Property Work?
- National Association of Realtors (NAR) — NAR Existing-Home Sales Report Shows 1.7% Decrease in July (2025-08)
- Clever Real Estate (ListWithClever) — Average Real Estate Agent Commission Rates: 2026 Survey
- Opendoor — How to Sell an Inherited House: Step-by-Step Guide for Heirs
- Opendoor (citing Nolo) — How Long Does It Take to Sell an Inherited House?
- SearchColumbusHomesOnline — Ohio Probate Timeline: How Long It Takes to Sell an Inherited Home in Franklin & Delaware County
- HomeAdvisor (via Bankrate) — How Much Does It Cost To Stage A House? (2025)
- Homes.com (citing NAR 2025 Profile of Home Staging) — How much does home staging cost? (2025)
- HomeAdvisor (via Rocket Mortgage) — How much does a home inspection cost in 2026? (2026)
- House Beautiful (republished by NAR) — How Much Does a Home Inspection Cost in 2025? –House Beautiful (2025)
- Geiger Law Office — Understanding Step-Up in Basis for Assets Upon Inheritance
Written by
Tobias Lindqvist
Tobias covers floor plans, renovation trends, and the small design decisions that change how a home works. He's suspicious of trends that promise to 'future-proof' a house. He prefers writing about function over finishes.